On June 12, 2026, SpaceX comes to public markets at $135 a share, a valuation near $1.75 trillion and about 107 times sales, among the most expensive equities ever brought to investors. Some of that price is artificial intelligence. Goldman Sachs, the lead underwriter, projects $322 billion of AI revenue in 2030 inside a $474 billion consolidated total, and it published that single segment line with nothing beneath it. The question worth asking before the roadshow talking points harden is not whether to trust the number. It is what the number is built from, and how much of it rides on Grok, the model Elon Musk names most often.

Break the aggregate into its parts and most of it has little to do with how good Grok is.

Start with the one piece that carries a documented price today: compute, which SpaceX earns as a landlord rather than as a model-maker. SpaceX rents capacity on Colossus 1, its original Memphis cluster, to rival labs. Anthropic pays about $1.25 billion a month under terms scoped through May 2029, and Google about $920 million a month from October 2026 through June 2029, each running its own models on SpaceX hardware. Those two contracts alone run near $26 billion a year, and not one dollar of it depends on Grok’s quality. The tenant’s model does the work, and SpaceX collects the rent.

Goldman broke out nothing below its total, so the rest has to be reconstructed from the disclosed contracts and published pricing. Built from the bottom up, the 2030 projection sorts into four blocks. Operational AI, the compute leasing plus the autonomy embedded in vehicles and the network, comes to roughly $92 billion, about 29% of the projection, and depends on Grok not at all. Grok itself, the language-and-reasoning model, comes to roughly $45 billion, about 14%. X-platform advertising adds roughly $12 billion, about 4%. The largest block by far, roughly $173 billion or about 54%, is a pure residual: the gap between what can be built from documented sources and Goldman’s much larger aggregate. Recon Analytics reads that residual as further compute and infrastructure growth, but nothing that we can see documents it, so the conclusion that compute and operational AI dominate the projection holds only if that reading is right. All four sizes are Recon Analytics estimates. Goldman published none of them.

That leaves Grok carrying about a seventh of the projection, roughly $45 billion by 2030, against revenue well under $2 billion in 2025, inside an AI segment the S-1 reports at $3.2 billion that year. The climb the projection assumes, from under $2 billion to $45 billion in four years, is the part of the SpaceX AI story that actually turns on Grok. At about 107 times sales, every dollar of projected revenue carries a steep premium, and the 14% exposed to Grok carries it like the rest.

That climb is not a given, and the people closest to Grok are the reason. Among AI users who name a primary tool, only 1.7% name Grok, and that base is the most male-skewed of any major assistant at 77.2% against 54.2% for the field. They adopt AI at work less than the field does and bring Grok to work least of any major tool, they are the least willing to pay more, naming $6.50 a month to upgrade against $11.70 for Claude’s users, and they name bias a concern most often, at 23.0% against 13.5% for the field. A revenue line built to reach $45 billion has to convert a base that is, for now, the hardest of the majors to convert. The counterweight sits in the same data. Grok’s accuracy rating climbed from clearly negative into positive territory in April and May 2026, and the users who already pay report good value for the money. That is early, directional evidence that the rebuild Musk describes may be reaching the product, even as the trust and bias gaps have not moved.

So the disaggregation points an investor toward a cleaner way to price the AI line. Pay for what Grok does today, which is real but modest: bounded jobs across X, Tesla, Starlink support, and SpaceX’s own engineering, none of them in a loop where a wrong answer costs a life or a mission. Then treat the run to $45 billion as an option on a rebuild that Musk says is underway, priced as a probability rather than a promise. Most of the $322 billion is landlord compute and operational autonomy that will earn or fail to earn on their own merits no matter what happens to Grok.

One sensitivity sits above the others, and it cuts the other way. The Anthropic and Google leases carry 90-day cancellation clauses, and Musk has described the Anthropic arrangement in public as limited to six months, which sits in tension with the headline term running to 2029. If those leases shorten, the operational base that anchors this whole reconstruction shrinks with them. That is the single largest swing in the picture, and it works against the compute revenue, not against Grok.

What to watch from here is narrow. During and after the roadshow, listen for what SpaceX and Musk claim about Grok’s role inside that AI number, because the gap between Grok’s small current revenue and the large role the selling story implies for it is the whole tension. Watch whether the compute leases hold their headline terms or shrink toward Musk’s six-month characterization. And watch whether the rebuild produces a materially better model rather than a better name. Price the parts, not the headline, and most of SpaceX’s AI number sits clear of Grok.

Source: Recon Analytics AI Pulse, US named-primary AI users, March through May 2026 (Grok n=744; field n=44,541).

Continue Reading
Access the full premium research report
View the executive overview, full table of contents, analyst insights, and purchase options for the complete PDF report.

Read the Full Report →

The simple story about wireless is a price war: multi-year price locks, free lines, cable carriers underselling the mobile network operators and fixed wireless exceeding everyone’s expectations. A more complex story is revealed by the MNOs detailed earnings results. The core price of connectivity has been flat for nearly four years while household income has increased. Net net? The carriers turned themselves into discount storefronts for the services they sell.

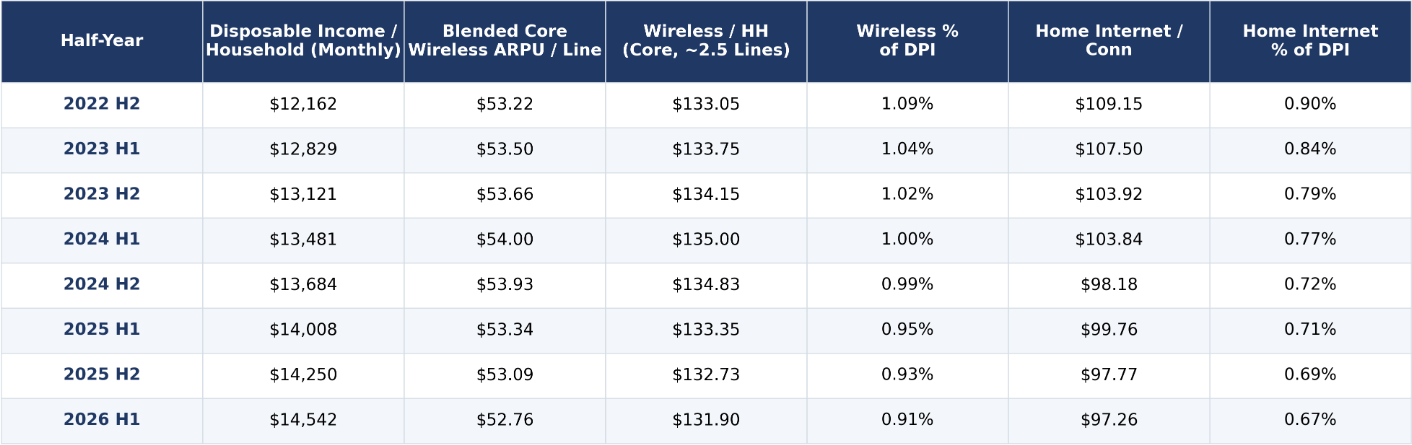
Reported wireless revenue per line looks like it climbed. Blended across AT&T, T-Mobile, and Verizon, postpaid phone ARPU rose from $53.22 in the second half of 2022 to $56.37 in early 2026, a roughly 6% rise. But Verizon, the carrier driving most of the 6% increase books streaming and cloud perks inside its reported ARPU. Its former consumer chief revenue officer stated publicly in March 2025 that 15% of wireless service revenue now comes from non-connectivity services, a figure that was zero when myPlan launched in May 2023 and is closer to 17% today. Strip the perks out on the same ramp, and the picture inverts. Blended core connectivity ARPU went from $53.22 to $52.76, flat to slightly down in nominal dollars across three and a half years.

Meanwhile, nominal disposable income per household climbed about 19% in the last four years according to the US government’s Bureau of Economic Analysis. Flat price, rising income, and the math is easy to understand.

Wireless is carrier-reported core ARPU (Verizon perk-adjusted). BEA NIPA per-capita nominal disposable personal income (series A229RC), scaled to household; real-terms adjustment uses the BEA DPI deflator (A229RC/A229RX); October 2025 onward extrapolated

Wireless fell from 1.09% of household disposable income to 0.91%, a 17% reduction in the relative burden, while the core price per line did not rise at all. That is the paradox in one line: ARPU went up, the price of connectivity did not, and telecom claimed less of the wallet driving real world savings for American families.

In real terms the gap is starker. Over the period the disposable-income price level rose about 9%, so a household’s real purchasing power grew roughly 9% rather than the full 19% nominal, while the core price of wireless, flat in nominal dollars, fell about 10% after inflation. The device is the one place inflation barely matters: the climb in smartphone selling prices is mostly premiumization, real buyers choosing more expensive phones, not the dollar losing value, with carriers footing for most Americans. Inflation-adjusted, connectivity got cheaper, incomes got larger, and only the hardware the consumer chose to upgrade got pricier.

While prices remained steady in the last several years, the value consumers are taking from their wireless providers has dramatically increased. Let’s look at Verizon by way of example.

Verizon is the lone nationwide carrier that books its perks into reported service revenue, about $10.50 per line by 2026, which is why Verizon alone takes the perk adjustment in the numbers above. The perks represent significant savings: Netflix and Max for $10 against roughly $18 bought separately, Apple One and Google One at about half of their near-$20 retail.

T-Mobile and AT&T deliver streaming without increasing their ARPU at all. T-Mobile folds Netflix into the plan and gives it away, and the Apple TV+ that shows up at $3 on a T-Mobile bill is passed straight through to Apple, not booked as T-Mobile service revenue. So two of the three nationwide carriers were already at clean core connectivity pricing, and only Verizon’s apparent climb was perks. The industry turned itself into a half-price, often free, storefront for streaming and cloud while holding the price of the pipe flat.

The value consumers are getting on the device side has increased as well. Consider the following. Recon Analytics Device Intelligence shows the sellout-weighted average selling price of a US smartphone reached $738 across 2025 and peaked at $868 in the fourth quarter, the iPhone 17 launch window, up from roughly $615 a year earlier. Forty percent of phones sold in 2025 cost $800 or more, and nearly one in five was a $999-and-up flagship. The market has finished its move to 5G: 93% of phones bought in 2025 were 5G-capable, so the network the carriers spent years building now sits in nearly every new device. Apple accounts for 57% of US units sold at an $884 average, Google’s Pixel tops the range at $992, Samsung holds a quarter of the market at $652, and Motorola anchors the value end at $285. consumers have access to better devices while the carrier absorbs the cost.

Nearly one in five phones sold still costs under $300, so the household that wants to spend less can, while carrier trade-in credits and multi-year interest-free financing put the $884 Apple within monthly reach for the household that wants the best.

For the American consumer, all of this adds up to one of the best deals in the household budget.

Wireless service runs about $130 a month for a typical multi-line household and has been flat in nominal terms since 2022, under 1% of disposable income and falling about 10% in real terms. For that, plus a device financed at zero interest with carrier generally crediting back the financing cost, the household carries a premium 5G phone whose $700-plus sticker it never felt, multi-year price certainty, and a stack of streaming and cloud services worth $25 to $45 a month at retail for a fraction of that or nothing. A family that would pay $40 to $50 assembling Netflix, a second streamer, and cloud storage on the open market gets the same through the carrier for $10 to $20, or free on T-Mobile. Connectivity is cheaper as a share of income than at almost any point in the smartphone age, the rising cost of the device is absorbed by the carrier, and the services that ride the network arrive at half price or no price.

The competitive read inverts the conventional wisdom. This was not a race to the bottom on price. Carriers held core connectivity prices flat for four years and grew revenue by selling discounted services the customer wanted, while the affordability cushion underneath quietly widened. Wireless now sits below 1% of household disposable income. At that level, a price increase is closer to noise in the family budget than the switching trigger it was when wireless approached 1.4%. The pricing power is real and underused, and the next dollar of revenue is far more likely to come from perks, premium tiers, and device economics than from the base plan. The strategic question is no longer how low the bill must go. It is how much value carriers can stack on a bill that already claims less of the paycheck than at almost any point in the smartphone age.

Continue Reading
Access the full premium research report
View the executive overview, full table of contents, analyst insights, and purchase options for the complete PDF report.

Read the Full Report →

The Question

In February 2026, OpenAI became the first major AI assistant to show ads to free users of ChatGPT. By March, the rollout had expanded to pilot markets in Canada, Australia, and New Zealand. The conventional read is that consumer AI is simply following the path of free email, free search, free social media, and free streaming: founders resist ads on principle, costs grow, and eventually they give in. Anthropic’s pledge to keep Claude ad-free, in this view, is Reed Hastings’ 2020 promise that Netflix would never need ads, a statement that aged poorly.

Our view differs. Ads will produce real revenue at OpenAI. But they will not drive the long-term growth of consumer AI. They will sit alongside it. This note explains why, and what it means for the three major players.

The Core Finding: The Free Tier Is Two Very Different Groups

Recon Analytics runs a monthly consumer survey of AI users in the United States, with tens of thousands of respondents monthly and data running from March 2025 through the present. The survey captures usage frequency, payment status, willingness to pay, and reasons for not paying, with enough sample to draw reliable conclusions across platform, income, and age segments.

The standard story treats free-tier users as one group to be monetized through ads. The data shows they are not.

Usage Segment Avg. WTP ($/mo.) Would Never Pay
Heavy users (multiple times/day) $11.80 18%
Casual users (few times/month) $4.92 38%

Source: Recon Analytics AI Pulse consumer survey, ChatGPT primary users on free tier, 2026 YTD, n=24,984.

Heavy users are economically a different population. They are not casual users who happen to open the app more often. The gap holds at every income level, across every age group from young adults to people in their late fifties, and across all five quarters of data, including the quarter in which the ad rollout launched.

The gap widens among higher-income households. Among users in $100K+ households, heavy free users report willingness to pay of $15.17 per month; casual users in the same bracket report $5.09. That is a 3x spread in the segment that should, by any reasonable theory, be most willing to pay overall.

The Strategic Problem with Ads

This matters because of where ads land. Ads are visible to all free users. The casual users see ads and stay casual, because nothing in their behavior suggests they were ever close to converting to paid. The heavy users see ads and bump up against friction in their main daily tool, at exactly the moment they were most likely to consider paying $20 a month to make it stop.

Ads generate inventory from the group that drives almost none of the cost. The friction lands on the group that drives most of the cost and was most ready to convert. The ad strategy monetizes the wrong half.

The trend data makes this more concerning. Heavy free users have been stable: between 13 and 18 percent say they would never pay, and the number has not moved since the ad launch. Casual free users are drifting in the wrong direction. In Q2 2025, 28.8 percent said they would never pay; by Q2 2026, that number was 36.8 percent. The group ads are aimed at is becoming structurally less convertible over time.

Platform Comparison: Not All Free Tiers Are Equal

The same logic applies to the other major AI assistants, with important structural differences.

Platform “Would Never Pay” (Free Users) Paid Retention (6-Mo.)
Claude ~22% 74%
ChatGPT ~24% 71%
Perplexity ~32% 74%*
Gemini ~37% 74%
Copilot ~39% 92%

Source: Recon Analytics AI Pulse consumer survey, 2026 YTD. Total n=43,738 (free tier); total paid n=11,965. Perplexity paid retention (n=169) is directional only.

The split between the top three and the bottom two is not random. Claude, ChatGPT, and Perplexity users mostly sought the product out. Gemini and Copilot users mostly arrived through distribution: Android devices, Google Workspace, Microsoft 365 enterprise licenses. Deliberate-choice users filter themselves on wanting the product before they ever sign up. Arrived-by-default users include a large fraction who would never have chosen the product actively.

Copilot’s 92 percent paid retention is not a subscriber satisfaction story. It reflects that most Copilot paid users are on enterprise Microsoft 365 licenses they cannot cancel individually. This is a good business for Microsoft. It is a structurally different business from what OpenAI and Anthropic are running, and modeling them as equivalent competitors produces misleading conclusions.

Three Predictions for the Next 18 Months

OpenAI. Ad revenue will scale. Published estimates of a $25 billion annual run-rate by 2030 are plausible, with a 2027 run-rate in the $4 to $8 billion range. But paid subscriber share, currently around 23 percent in our data, will not improve materially. It will stay between 20 and 26 percent through the end of 2027. Ads produce a separate revenue line. They do not pull conversion higher.

Anthropic. Claude’s free users currently convert to paid at roughly 43 percent, nearly double the ChatGPT rate. That gap will narrow as the base grows, because the current user base skews toward self-selected early adopters who are unusually likely to pay. But the gap will not close. Claude should still be converting at least 10 percentage points ahead of ChatGPT by end of 2027. Claude’s paid subscriber base, which has been growing roughly 2.5x every five months through early 2026, will be 2 to 4 times its current level by Q4 2027. The ad-free positioning is working as a business strategy, not just a marketing slogan.

Google. Gemini will carry ads inside the standalone app before the end of 2027. When consumer AI revenue is fully disaggregated, standalone Gemini subscriptions will be a smaller fraction of the total than commonly assumed. Most of what gets reported as “Gemini consumer monetization” is Google One bundle revenue and AI Mode search advertising. Gemini’s economics make sense modeled against Copilot, not against ChatGPT. The one thing Google I/O 2026 adds to this picture: the agentic commerce layer opens a revenue path that bypasses the subscription question entirely, which could make Google’s consumer AI economics work even if conversion stays low.

The Bottom Line

Ads will not solve the core economic challenge of consumer AI. The challenge is converting heavy free users into paying subscribers fast enough to cover the very high cost of serving them. Ads charge friction on the users who drive the cost and were most ready to pay. They extract small revenue from the users who drive little cost and would never have paid anyway.

The companies best positioned to win the consumer AI category are not the ones with the cleverest ad products. They are the ones that figure out how to convert heavy free users into paid subscribers at a higher rate. Anthropic is currently doing this at nearly double the ChatGPT rate, on a smaller base. Whether that advantage holds as the base scales is the most important question in consumer AI monetization over the next 18 months.

For the full analysis including counter-arguments and detailed breakdowns by income and age cohort, see The Wrong Half: Why Ads Will Not Fix Consumer AI’s Money Problem, Recon Analytics, May 2026.

Source: Recon Analytics AI Pulse consumer survey, periods March 2025 to April 2026.

Continue Reading
Access the full premium research report
View the executive overview, full table of contents, analyst insights, and purchase options for the complete PDF report.

Read the Full Report →

In one week in mid-May 2026, three events reshaped the analytical surface in US wireless. On May 12, the FCC approved SpaceX’s purchase of 65 megahertz of nationwide Direct-to-Device spectrum from EchoStar under tech-neutral performance obligations, replacing the December 14, 2026 buildout cliff with a continuous performance standard. Four days later, AT&T, T-Mobile, and Verizon announced a satellite Direct-to-Device joint venture in principle. The announcement carried no name, no spectrum allocation, no governance structure, no capital commitment, and no launch date. A week after that, SpaceX filed its Form S-1, the document the IPO market will use to price the integrated platform across the next several quarters. The S-1 positions SpaceX as the global satellite wholesale supplier to mobile network operator partners. The operating pattern points somewhere else.

The Seven Pieces

Between February 2024 and May 12, 2026, SpaceX assembled seven operating pieces of a US consumer mobile capability that no wholesale supplier needs.

Spectrum: 65 megahertz of nationwide allocation (15 MHz AWS-3 unpaired, 40 MHz AWS-4, 10 MHz PCS H-Block) dedicated to Direct-to-Device, under technologically neutral performance obligations that allow terrestrial, space-based, or hybrid deployment.

Power: a 770 percent power increase from the FCC’s March 2025 waiver, enabling Direct-to-Cell to carry T-Satellite messaging at the July 2025 commercial launch and full data plus WhatsApp voice and video at the October 2025 expansion.

Capacity: the April 30, 2026 NGSO spectrum-sharing overhaul allows up to eight satellites simultaneously per area-and-frequency cell against the prior limit of one. Chairman Carr’s read is up to a 700 percent capacity boost for LEO broadband.

Satellite count: 7,500 additional Direct-to-Cell Gen2 satellites approved in January 2026 under a 15,000-satellite filing, independent of the legacy Starlink internet constellation and purpose-built for cellular use under the elevated power regime.

Brand: USPTO trademark applications for “Starlink Mobile” and “Powered by Starlink,” filed October 16, 2025, covering consumer cellular on the face of the application.

Network identity: ITU-T E.212 records SpaceX as the assigned operator of MCC 901 MNC 08, effective February 1, 2024. A SIM provisioned for SpaceX would see SpaceX as a registered Public Land Mobile Network in the device’s network-selection menu.

Gen2 platform: the deployment platform for the 3GPP 5G non-terrestrial network standard, reaching consumer-grade operationalization across 2027 and converting Direct-to-Cell from a data-and-messaging overlay into native cellular voice at consumer scale on the platform SpaceX controls.

The wholesale-supplier model needs satellites and capacity. The MNO destination needs all seven.

The Pattern Argument

The S-1 commits to expanding the global MNO partnership network, deploying V2 Mobile satellites in 2027, closing the EchoStar spectrum acquisition in November 2027, and achieving 5G non-terrestrial network compliance for unmodified devices through MNO partner pressure on handset manufacturers. It does not commit to becoming a US consumer MNO. The growth-strategy language describes “providing connectivity for everyone” through partnership expansion. The risk-factor section names an option: “either by operating on spectrum leased to us by MNO partners or by utilizing our own domestic spectrum holdings.” The option is preserved on the page. The commercial strategy is wholesale.

The operating pattern reads differently. Strip a $50-per-month US wireless subscription to its inputs. The gap between ARPU and the cost to provide service is larger than five times. The two-decade pattern across rockets, batteries, AI compute, and satellite manufacturing reads that gap as organizational waste and attacks it with a vertically integrated build. SpaceX has not signed an MVNO agreement anywhere in the world; the thirty international MNO partnerships are the inverse arrangement, with SpaceX as the upstream supplier. T-Mobile’s T-Satellite in the US is the same template. The wholesale-supplier model is what SpaceX has been running, not what the documented pattern points toward over the three-year IPO-priced optionality horizon.

The Carrier Signal

The carriers read the pattern. The May 16 joint-venture announcement arrived inside the 96-hour window between the FCC approval and the SpaceX IPO disclosure cycle opening. Five attributes diagnose its purpose: no name, no spectrum allocation, no governance structure, no launch date, and explicit preservation of each carrier’s bilateral satellite relationships. T-Mobile keeps T-Satellite with Starlink. AT&T keeps its AST SpaceMobile partnership and adds the new EchoStar-Boost MVNO. Verizon keeps its AST SpaceMobile commercial agreement signed October 8, 2025. The JV pools nothing operational. It is a position-marker placed before the strategic response had been negotiated.

The market initially treated the JV as a defensive moat against SpaceX. A sharper diagnosis: the JV is the carriers’ alarm signal at SpaceX’s growing market power in satellite telecom, expressed in announcement form before the strategic response had been articulated. The S-1 does not disclose the direct-MNO commitment the carriers are reacting to. The carriers are reading the operating pattern, not the disclosure document. They are reading correctly.

The Funding Architecture

The IPO funding architecture has a feature that prior reports could only sketch. The S-1 confirms total EchoStar consideration of approximately $19.6 billion, comprising approximately $11.1 billion in equity (261.8 million shares at $42.40 per share) plus up to $8.5 billion to pay off designated EchoStar debt. The SpaceX Bridge Loan signed March 2, 2026 was used to repay X and xAI notes following the February 2026 SpaceX-xAI merger, and requires repayment from net IPO proceeds. The IPO is therefore part debt-refinancing event and part growth-capital raise. The mix matters for what the proceeds actually fund.

The Anthropic compute partnership announced May 6, 2026 covers Colossus 1 at more than 300 megawatts and more than 220,000 NVIDIA GPUs, analyst-reported at roughly $5 billion annually. The Connectivity segment generated $7.2 billion in Segment Adjusted EBITDA in 2025, nearly double 2024, with Starlink Subscribers at 10.3 million by Q1 2026, up 105 percent year-over-year. The broadband engine funds the integrated capital plan regardless of how mobile activation lands.

Two Paths to MNO

The platform reaches the MNO destination on either of two paths.

The host path: a nationwide MNO agrees to host Starlink Mobile on wholesale terms. The carrier is the invisible network underneath; the customer-facing brand is Starlink. The case is structurally real but commercially constrained on every side. Each nationwide MNO already carries at least one bilateral satellite counterparty commitment, and the cost of breaching or renegotiating an AST commercial agreement raises the threshold for a host move at AT&T and at Verizon. The base-case read is that none of the three breaks inside the IPO disclosure window.

The direct path: SpaceX builds the terrestrial fill itself. AWS-4 second-step assignment closes November 30, 2027 and SpaceX takes direct operational control of the spectrum. 5G non-terrestrial network consumer-grade operationalization on Gen2 satellite hardware in 2027 lights up native cellular voice on SpaceX-controlled spectrum. The engineering layer reaches commercial scale in late 2027 to early 2028. The institutional-knowledge layer (state-by-state PUC compliance, lawful intercept architecture, E911 service-level architecture, port-in coordination, customer support at scale) ramps on its own clock for an additional 12 to 24 months. The realistic operational read for consumer scale is 2029 to 2030, not 2028. The IPO market prices the destination at the headline; the post-IPO trading window prices the institutional layer at the discount.

What to Watch

Three observable events between July 2026 and Q1 2028 falsify the direct-MNO thesis. First, if SpaceX’s X-channel statements through Q3 2026 sustain the wholesale-supplier framing rather than re-frame the carrier denials as bad-faith obstruction. Second, if the T-Satellite exclusivity expiry on July 23, 2026 lands as a quiet termination with no SpaceX-side renegotiation drama. Third, if the November 30, 2027 AWS-4 second-step assignment closes and is followed within ninety days by a public SpaceX commitment to wholesale-lease the spectrum rather than to direct deployment. Two of three observed compress the direct path’s probability materially. All three convert the pattern thesis from direct-MNO-with-wholesale-transition to wholesale-with-optionality as the durable end state.

The IPO disclosure window opens in June 2026. The road show prices what the S-1 says. The post-IPO trading cycles will price what the operating pattern is committed to. The S-1 says wholesale. The pattern says MNO.

Continue Reading
Access the full premium research report
View the executive overview, full table of contents, analyst insights, and purchase options for the complete PDF report.

Read the Full Report →

May 2026

Satellite internet used to mean one thing in the business world: a slow, expensive connection of last resort when nothing else was available. HughesNet and Viasat filled that role for years, and nobody was excited about it. LEO satellite operators, including Starlink, have changed that story. Lower latency, faster speeds, and a product that can actually compete with fixed wireless have moved satellite from the back of the options list to a legitimate part of businesses’ connectivity fabric. However, even with greater acceptance of LEO satellite communications, Starlink still has a limited market position.

The Coverage Gap Story

The strongest direct sales case for Starlink in business markets is the coverage gap. Go where the competition does not. It sounds simple, and in a lot of ways it is.

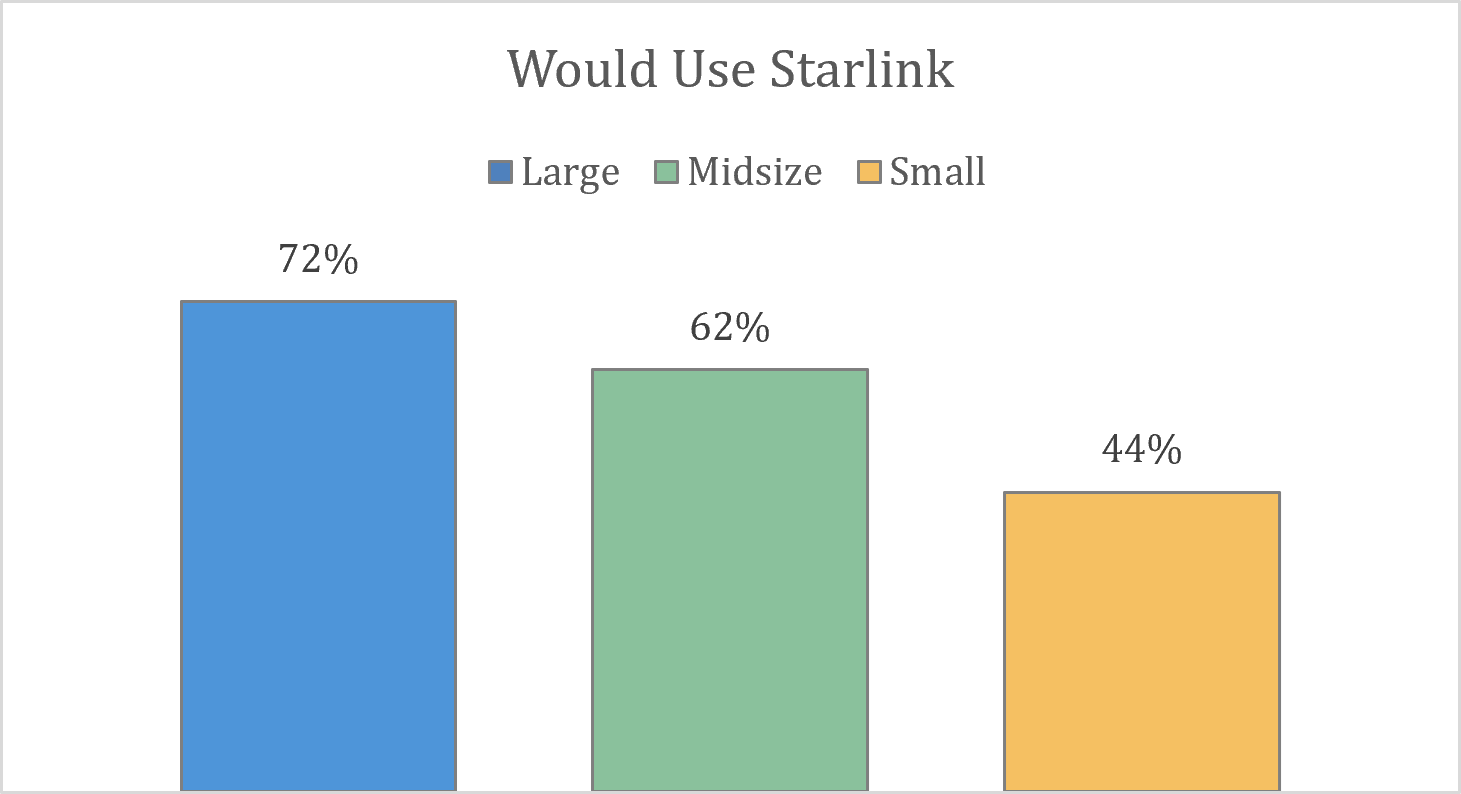
Between March 4 and April 7, 2026, we asked businesses whether they would work with a smaller ISP if that ISP could deliver Starlink connectivity in places where they currently had no coverage (Large n=586, Midsize n=455, Small n=554). Large businesses came in at 72%, midsize at 62%, and small businesses at 44%. The 28-point spread between large and small is the part worth paying attention to. Large businesses are most receptive because they are most likely to already be living with this problem. A company with 50 locations almost certainly has some of those locations sitting outside fiber and cable reach. A small business with one rural location either has the problem or it does not. For the large enterprise managing a dispersed footprint, a Starlink-augmented ISP solves something concrete and immediate.

Figure 1. Percent of Respondents Who Would Work with a Smaller ISP if They Augmented Coverage with Starlink

Source: Recon Analytics 3/4/2026-4/7/2026, Large n = 586, Midsize n = 455, Small n = 554

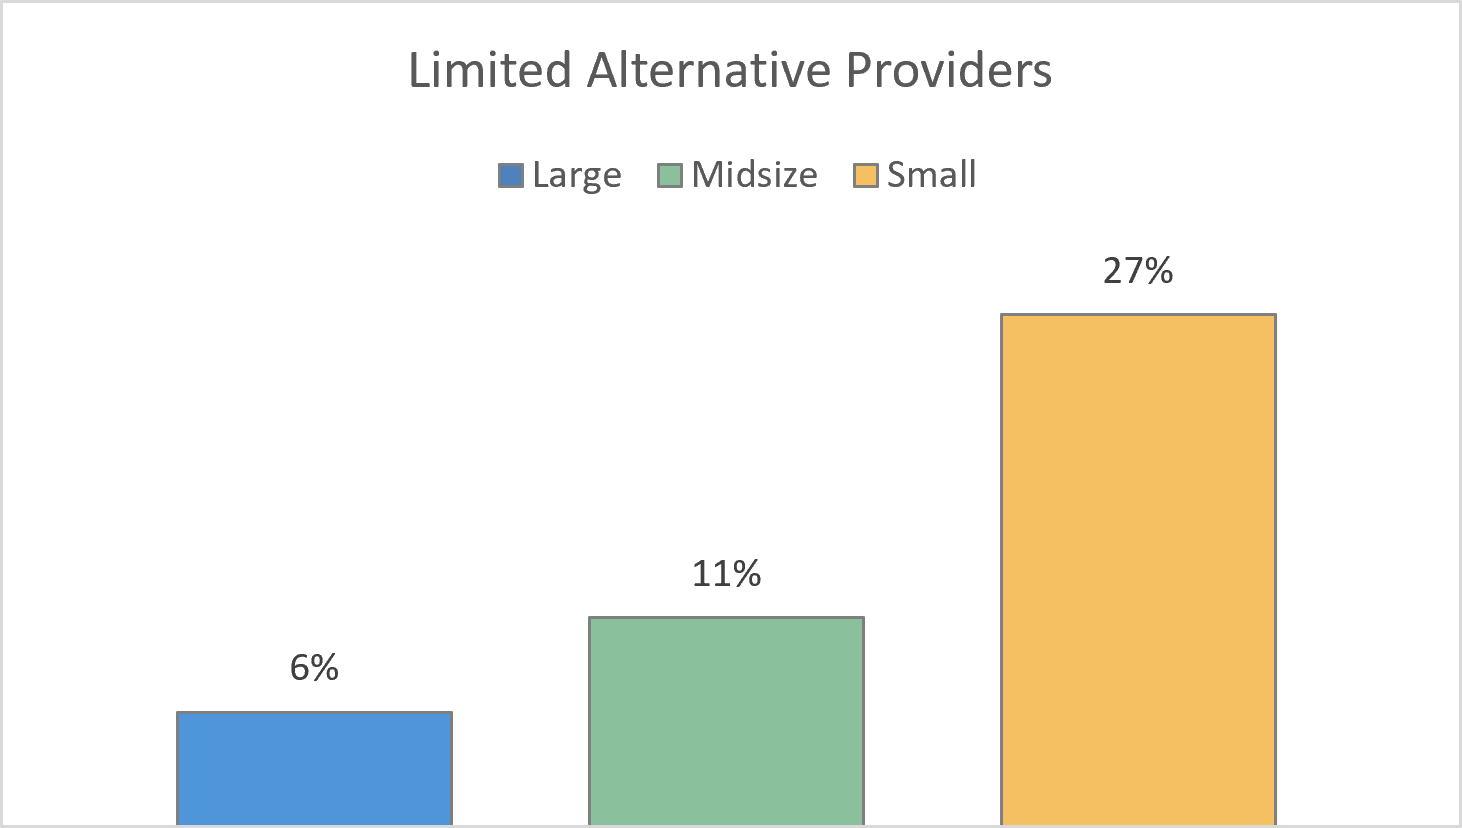
The second piece of data that helps to illustrate the coverage gap opportunity for Starlink comes from a different question. Between November 5, 2025, and May 6, 2026, we surveyed 9,913 businesses and found 1,483 that were unhappy with their current internet provider but had not switched. Among small businesses in that group, 27% said the reason they had not left was simple: there were no other options. For midsize businesses it was 11%, and for large businesses just 6%.

That 27% small-business figure is where Starlink’s direct-sales pitch is at its strongest. When a business is stuck with a provider they dislike because there is literally nothing else, Starlink is not going head to head with a well-resourced competitor. It is filling a gap that nobody else is filling. That is a very different conversation.

Figure 2. Limited Alternative Internet Provider as Reason to Stay with Current Provider

Source: Recon Analytics 11/5/2025-5/6/2026, Large n = 361, Midsize n = 502, Small n = 620

Moving outside of areas with little to no broadband access will be more difficult for Starlink as larger businesses do not just buy connectivity from their ISPs. Larger businesses buy a full suite of solutions including security, direct cloud connectivity, and SD-WAN. These are all services that Starlink does not provide. Starlink, currently, just provides connectivity.

The FWA Backup Case

The satellite-as-backup to primary internet access is Starlink’s other major business connectivity opportunity. Starlink does not need to win the primary internet relationship here. It just needs to be there when the primary connection goes down.

AT&T and Verizon already do something similar with FWA. Both service providers use their FWA network as a failover solution incase the primary internet access line they provide should have an outage. Satellite can provide the same function in areas where FWA is not available or where FWA is the primary access technology.

Recon Analytics tested this concept directly with U.S. businesses during the first half of 2026. Between April 1 and April 29, 2026, we asked businesses whether satellite backup would make FWA a more attractive primary connection (Large n=525, Midsize n=464, Small n=563). Large and midsize businesses both came in at 34%. Small businesses were at 24%. These numbers predate T-Mobile’s SuperBroadband announcement in May 2026, which matters. Starlink failover is one of key features of SuperBroadband. This is demand that existed before the product launched, not demand manufactured by a marketing push.

The practical reality, though, is that the FWA backup opportunity mostly runs through carriers, not through Starlink’s direct sales team. T-Mobile owns the customer relationship in SuperBroadband. Comcast Business owns it in its managed connectivity offering which utilizes Starlink as well. That is a lower-margin model than selling direct, and it means accepting a role as infrastructure provider rather than service provider. The upside is scale. Carrier channels can reach enterprise accounts and multi-location businesses that Starlink cannot do as efficiently on its own.

The longer-term question for Starlink is whether it stays in that infrastructure role or eventually moves to compete directly in markets where carrier partners currently hold the customer. Nothing in Starlink’s commercial agreements with T-Mobile or Comcast prevents it from doing so. The constraint right now is product fit, not contract language. That distinction is worth keeping in mind when thinking about how durable these partnerships really are. The recently announced joint venture between AT&T, T-Mobile, and Verizon on direct-to-device satellite communications could complicate Starlink’s relationship with T-Mobile and be a catalyst for Starlink to take a more aggressive role in selling directly to businesses.

Continue Reading
Access the full premium research report
View the executive overview, full table of contents, analyst insights, and purchase options for the complete PDF report.

Read the Full Report →

Apple gained 6.3 points in installed-base share among 18-to-29-year-old US smartphone users from Q3 2025 to Q1 2026. Exclusive loyalty in the same cohort is 12.3 percent, 23 points below the 60-plus reading.

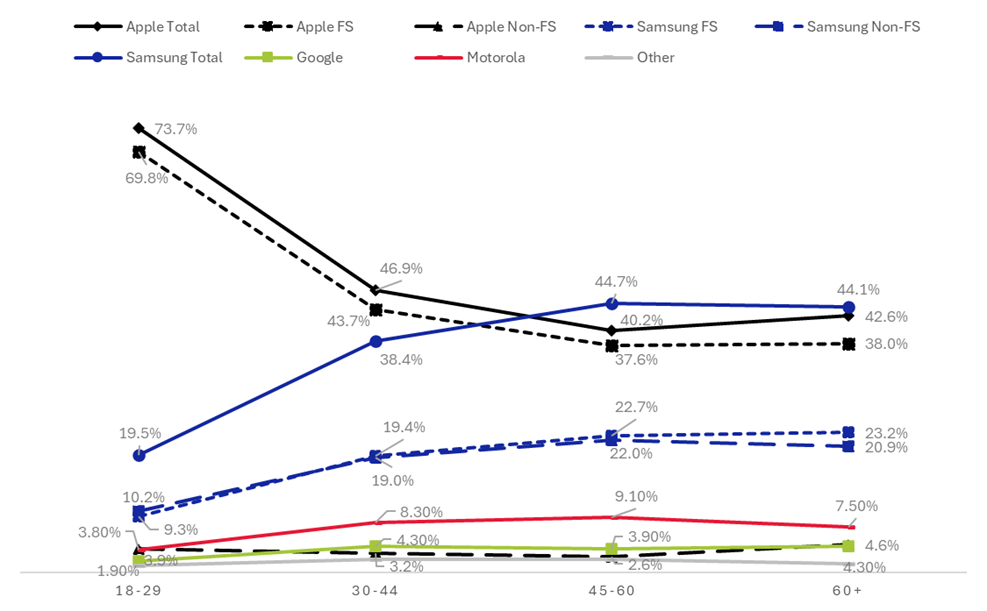
In the US smartphone installed base, Apple commands the 18-to-29 cohort at 73.7 percent share across the combined Q3 2025 to Q1 2026 window, more than three times Samsung’s combined 19.5 percent. Behind that combined reading, the trend is also moving in Apple’s favor. Apple’s 18-to-29 share rose from 68.9 percent in Q3 2025 to 75.2 percent in Q1 2026, a 6.3-point gain in nine months that is well above the margin of error.

Table 1: Apple 18-to-29 Installed-Base Share by Quarter
Quarter Apple Share Samsung Flagship Share
Q3 2025 68.9% 11.3%
Q4 2025 76.3% 7.9%
Q1 2026 75.2% 9.1%
Combined 73.7% 9.3%
Source: Recon Analytics Consumer Pulse Survey, Q3 2025 through Q1 2026, smartphone-only

The data come from Recon Analytics’ Consumer Pulse Survey, covering 248,279 US smartphone respondents tracked from Q3 2025 through Q1 2026, with respondents’ device brand and model identified via passive detection at survey entry rather than self-report. Apple’s installed base is 93.2 percent in the premium tier and 6.8 percent in the value tier. Samsung’s installed base splits roughly 50-50 between Samsung Flagship and Samsung Non-Flagship.

The age-cohort gap closes sharply by 45-plus and then reverses. Samsung’s combined book reaches 44.7 percent of the 45-to-60 cohort and 44.1 percent of the 60-plus cohort, its highest installed-base concentrations across the four cohorts tracked. Apple’s combined share in those same cohorts falls to 40.2 percent and 42.6 percent. At the brand-total level, Samsung’s installed base exceeds Apple’s at 45-plus, an inversion of the 18-to-29 reading.

Chart 1: US Smartphone Installed-Base Share by Age Cohort

Inside the comparable premium tier, the gap compresses even more sharply than the brand-level numbers indicate. Apple Flagship leads Samsung Flagship across all age cohorts. In the 18-to-29 cohort, Apple’s flagship installed-base share is 69.8 percent, compared with Samsung’s 9.3 percent, a 60.5-point gap. By the 60-plus cohort, Apple Flagship is 38 percent compared with Samsung Flagship at 23.2 percent, a 14.8-point gap. The Apple Flagship lead in the youngest cohort is more than four times that in the oldest cohort. The premium tier is closely contested at 45-plus in a way the youth-cohort dominance does not predict.

When Samsung’s combined installed base is plotted against Apple’s, Samsung Total runs 4.5 points above Apple in the 45-to-60 cohort and 1.5 points above in the 60-plus cohort. That convergence reflects portfolio coverage rather than head-to-head premium competition. Samsung addresses every price band in the US smartphone market, from sub-200-dollar Galaxy A devices to the 1,900-dollar Z Fold. Apple addresses only the premium tier, with a value-tier presence at the SE and 16e price points that does not extend below $599. The combined-book comparison sums two different addressable markets. Inside the comparable premium tier, no cohort crossover exists.

Within the same nine-month window, the premium-tier picture varies across cohorts. Apple’s lead over Samsung Flagship in the 18-to-29 cohort widened from 57.6 to 66 percentage points across the window, the most decisive premium-tier movement in the dataset. In the 45-to-60 cohort, the same lead narrowed from 16.7 to 15 percentage points. In the 60-plus cohort, the compression was sharper: from 19.4 to 16 points. The premium tier is sorted by generation. Apple is consolidating among young buyers; Samsung’s flagship is gaining ground among older buyers.

The combined Q3 2025 to Q1 2026 window includes the iPhone 17 launch quarter (Q4 2025), which produced a sharp Apple gain across all cohorts, partially reverting in Q1 2026. The within-window quarterly cuts isolate that effect: Apple’s 18-to-29 share peaked at 76.3 percent in Q4 2025, then settled at 75.2 percent in Q1 2026. The Q1 2026 reading is the most recent post-launch quarter and remains 6.3 points above the Q3 2025 entry.

The 18-to-29 cohort that is moving most decisively toward Apple is also the iPhone segment that cross-shops the most in the dataset. Exclusive Apple loyalty (don’t consider any other brand at all) among 18-to-29 iPhone users is 12.3 percent, the lowest of any age band tracked. Among consumers over 60, exclusive Apple loyalty reaches 35.2 percent, almost three times higher. The young Apple user holds an iPhone today and is also the most open to switching brands for the next purchase.

Table 2: Apple Exclusive Loyalty by Age Cohort
Age Cohort Apple Exclusive Loyalty
18-29 12.3%
30-44 13.6%
45-60 23.9%
60+ 35.2%
Source: Recon Analytics Consumer Pulse Survey, Jul 2025 through Jan 2026, smartphone-only

The combination is unusual. Rising share with low exclusive loyalty indicates Apple is acquiring new young users at scale rather than locking in the ones already there. Position is rising; lock-in is not. Cross-brand consideration data confirms the openness: among 18-to-29 Samsung Flagship users, 30.6 percent considered Apple before their most recent device purchase, the highest cross-Apple consideration rate of any cohort and brand combination in the report. Older cohorts narrow their consideration sets dramatically. Among Apple users over 60, exclusive loyalty at 35.2 percent means more than one in three did not consider any other brand at all. The same shopper behavior that drives high cross-shopping in the young cohort also yields a stable share among older cohorts. Apple is winning the conversion contest in this cohort. Cross-shopping consideration runs both ways, but the realized installed-base share movement of 6.3 points net runs to Apple.

Google’s installed-base share never exceeds 4.3 percent in any age cohort. Motorola peaks at 9.1 percent in the 45-to-60 cohort. Neither brand’s age curve approaches the spread shown by Samsung Flagship or Apple Flagship in the premium tier. The mass-market US smartphone story is an Apple-Samsung story; Google and Motorola compete inside narrower segments.

What this picture suggests for OEM and carrier strategy is asymmetric. Apple’s 18-to-29 share gains arrive without the loyalty buffer that the 45-to-60 and 60-plus shares carry. Samsung Flagship’s natural addressable opportunity is not in the cohort it has lost most ground in, but in the 60-plus cohort, where the premium-tier gap is narrowest and where the brand’s combined book already exceeds Apple’s. Carrier-led upgrade campaigns converting Samsung Non-Flagship users to Galaxy S face different population profiles across target cohorts. The young cohort that Apple is gaining is also the cohort most likely to consider switching.

The Galaxy S26 launched in January 2026, within the most recent quarter in the data window. Q2 2026 will be the first full post-launch quarter to confirm whether Samsung Flagship’s 18-to-29 decline is a structural pattern or a launch-cycle artifact.

Apple’s 38 percent Flagship installed-base share among 60-plus consumers represents the brand’s smallest cohort lead. The structural question is whether today’s 18-to-29 cohort, which has the lowest level of exclusive Apple loyalty in the market, stays with Apple as it ages. The share gains in 18-to-29 are real. So is the openness to change.


This article draws on the demographic findings of Recon Analytics new report, US Consumer Device Purchase Journey Part 4: Demographic Segmentation and the Upgrade Pipeline. The full report covers gender, ethnic community, geographic, consideration, and feature-priority segmentation across all four major US smartphone brands, plus quarterly trend cuts from Q3 2025 to Q1 2026.

If you are interested in the full report, you can find it here:
Digital Products – Recon Analytics

Verizon’s nationwide wireless outage on January 14, 2026, was the kind of event that doesn’t just disrupt a Tuesday: it hands every competitor field rep a talking point they’ll use for the next 18 months. Recon Analytics surveyed 1,702 business decision-makers between January 21 and February 25, 2026, capturing reactions in the immediate aftermath. The results tell a story that is both better and worse for Verizon than the company probably wants to hear.

The Outage Was Not Felt Equally

The January 14 outage was not a uniform experience across the business market. Impact scaled with company size, and the 23-percentage-point spread between large and small business is the first structural finding.

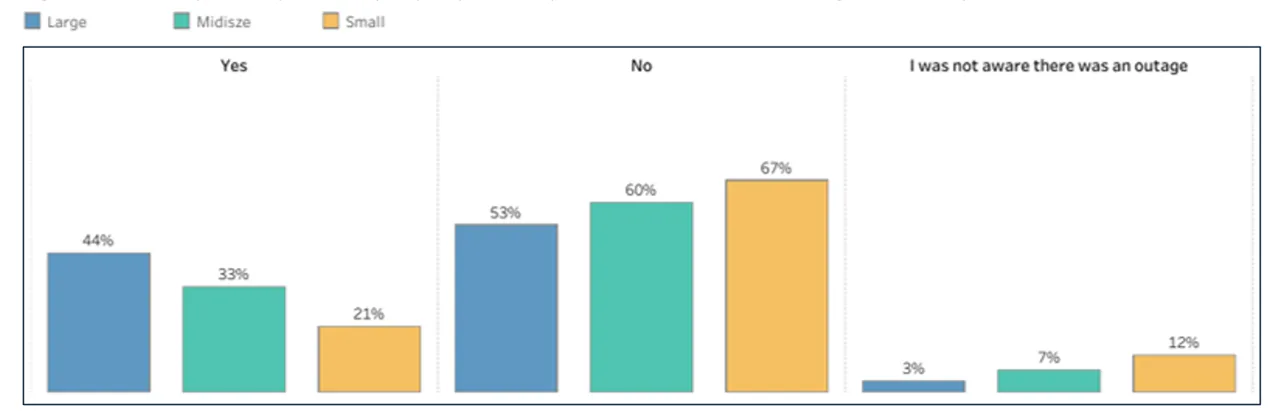
Large businesses reported the highest direct impact: 44% said the outage affected their company. Midsize companies came in at 33%. Small businesses sat at 21%. The remaining respondents in each segment indicated either no impact or were unsure. The gradient makes operational sense. Large organizations run more lines, more devices, more mission-critical workflows over wireless. A national field service operation or a distributed retail chain has thousands of points of exposure. A five-person shop has a handful. The outage hit large businesses hardest because they have the largest surface area. Large enterprises also operate more redundancy infrastructure, dedicated IT, secondary carrier contracts, Wi-Fi fallback. Whether the 44% figure reflects greater network dependency or greater issue-reporting sensitivity is not separable from this data.

The awareness data runs in the opposite direction. Among small businesses, 12% said they weren’t even aware an outage had occurred, compared to 3% of large enterprises and 7% of midsize. Small businesses run lean. If the phones worked well enough that day, or if the outage was brief enough in their geography, it didn’t register as a business event. Large enterprises have someone whose job is to know when the carrier goes down.

This awareness asymmetry matters for Verizon’s sales team. The enterprise segment felt the outage acutely and paid attention. That’s also the segment where Verizon has historically leaned on network reliability as its core value proposition. The pitch is that you pay more because the network doesn’t go down. January 14 complicated that pitch in the accounts where it matters most.

Figure 1: Was anyone in your company impacted by the Verizon Wireless outage of January 14th, 2026?

Source: Recon Analytics B2B Pulse, January 21st-February 25th, 2026. Percentages based on business respondents. Total n = 1,702, MoE = 2.4%; Large Business (1,000+ employees) n = 561, MoE = 4.1%; Midsize (20-999 employees) n = 538, MoE = 4.2%; Small Business (<20 employees) n = 603, MoE = 4.0%

Opinion Change Was Contained, Not Neutral

Among business customers who were aware of the outage, stated opinion change was limited. Across all size segments, roughly two-thirds said the outage did not change their opinion of Verizon. Opinion stability was statistically consistent regardless of company size.

The more operationally significant data is among those whose opinions did shift. Roughly 5-6% across segments said, “much more negative” and 27-29% said “somewhat more negative.” Combined negative sentiment ran approximately 32-35% across all segments. For an event that hit on a single day lasting about 10 hours, generating negative opinion change in roughly a third of aware business customers is a credibility problem if the narrative isn’t actively managed.

One caveat on the “no change” majority: it captures two distinct customer types that the data cannot separate. The first is the genuinely loyal customer who considers this within the bounds of acceptable carrier performance and has no intention of changing anything. The second is the customer who already held a neutral or negative opinion of Verizon before January 14, who are already at risk of leaving. Both sit in the same response bucket. The data cannot tell you how large each population is.

 Figure 2: (only if impacted by outage) How has the network outage changed your opinion of Verizon Wireless?

Source: Recon Analytics B2B Pulse, January 21st-February 25th, 2026. Percentages based on business respondents who indicated they were impacted by the outage. Total n = 551, MoE = 4.2%; Large Business n = 246, MoE = 6.2%; Midsize n = 179, MoE = 7.3%; Small Business n = 126, MoE = 8.7%

The Loyalty Question Is Where the Size Gap Becomes a Revenue Conversation

Because no pre-outage baseline is available for switching intent in this sample, the figures below represent a post-event snapshot, not a measured change from prior intent levels.

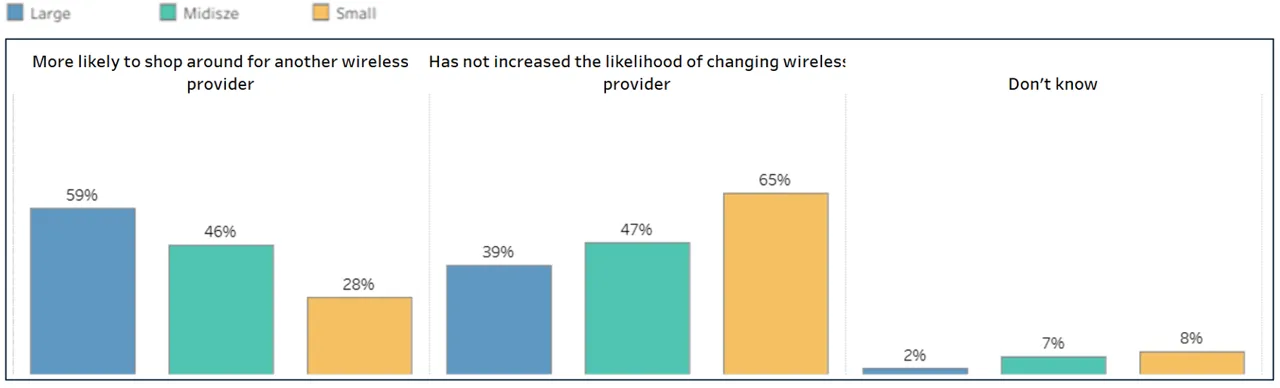
Among current Verizon Wireless business customers asked how the outage affected their likelihood of staying after their current agreement, small businesses were the most forgiving: 65% said the outage had not increased their likelihood of changing providers, 28% said they were more likely to shop around, and 7% were unsure or did not respond. Large businesses showed a different picture, with 39% saying the outage had not increased their likelihood of switching, 59% said they were more likely to evaluate alternatives, and 2% were unsure. Midsize was a statistical tie.

Among large business Verizon customers, 59% said the January 14 outage made them more likely to evaluate alternatives when their contract comes up. Remember, intent to shop is different from switching. Contract lock-in, device payoff schedules, multi-line complexity, and the operational headache of migrating a large business all create meaningful friction between stated intent and revealed behavior. Enterprise switching intent historically overstates eventual switching behavior. Even accounting for that gap, a post-event snapshot where 59% of large business Verizon customers express elevated interest in alternatives is a leading indicator that the competitive pipeline has expanded.

Enterprise wireless agreements typically run one to three years. The cohort of large accounts whose contracts expire in 2026 and 2027 is now at elevated churn risk compared to January 13. Verizon’s enterprise sales team should be in front of those accounts before AT&T and T-Mobile arrive with a pitch deck that opens on January 14.

 Figure 3: (currently using Verizon) How did the outage impact the likelihood of you staying with Verizon Wireless at your next renewal?

Source: Recon Analytics B2B Pulse, January 21st-February 25th, 2026. Percentages based on business respondents who self-reported current Verizon Wireless use. Total n = 510, MoE = 4.3%; Large Business n = 201, MoE = 6.9%; Midsize n = 167, MoE = 7.6%; Small Business n = 142, MoE = 8.2%

The Non-Verizon Market: Enterprise Forgives, Small Business Does Not

Among business customers not currently on Verizon, the outage produced differentiated responses that also track with company size.

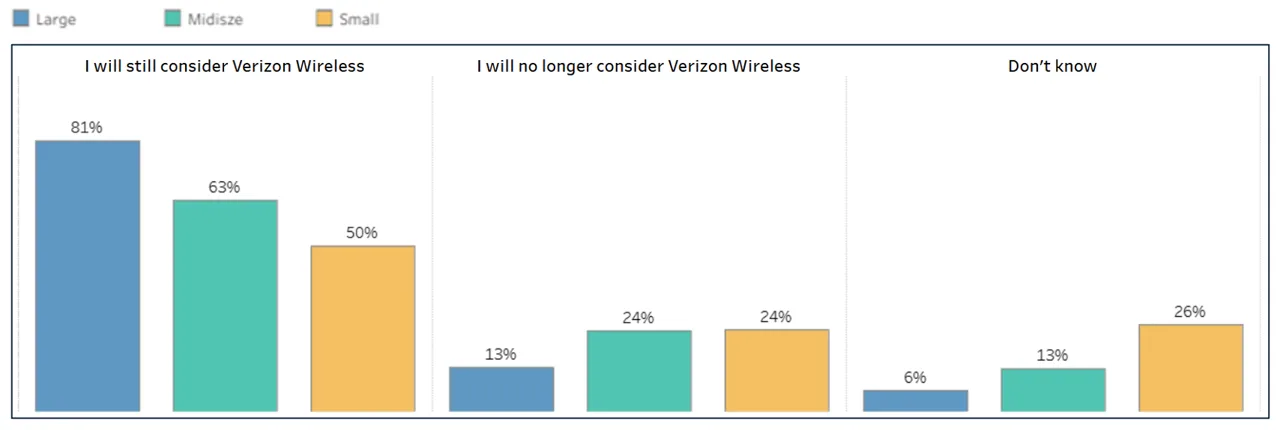
Large businesses remained the most open to Verizon despite the outage: 81% said they would still consider Verizon when their current agreement expires. One bad day doesn’t remove a major carrier from consideration. Enterprise procurement decisions involve pricing, coverage, device ecosystems, and account support infrastructure. Small businesses reacted more negatively to the outage, even though they did not experience the outage directly. 24% of small businesses said they would no longer consider Verizon, while 26% said they were unsure. A single outage is a data point, not a disqualifier, but can unbalance customers that are on the fence.

Figure 4: (Not currently using Verizon) How did the outage impact the likelihood of you considering Verizon Wireless next?

Source: Recon Analytics B2B Pulse, January 21st-February 25th, 2026. Percentages based on business respondents who do not use Verizon Wireless (self-reported). Total n = 1,064, MoE = 3.0%; Large Business n = 341, MoE = 5.3%; Midsize n = 334, MoE = 5.4%; Small Business n = 389, MoE = 5.0%

What Verizon Has to Do Now

The January 14 outage created a two-front problem. In the existing base, large business accounts are at elevated renewal risk. In the prospect market, small businesses have partially written Verizon off. But both are addressable.

Verizon’s enterprise team should prioritize proactive outreach to its large account base before those contracts expire. Generic reliability commitments won’t land. The message needs to be specific: what failed, what was fixed, what redundancy was added, what the SLA improvement looks like going forward. Enterprises don’t need apologies. They need engineering answers.

On the prospect side, the small business perception problem is harder because it’s driven partly by information Verizon doesn’t control. The counter-narrative has to reach small business decision-makers through channels they trust: peer networks, trade media, and the resellers and agents who carry Verizon’s products into that segment.

The January 14 outage was one bad day, which must be addressed with customers to protect accounts that could take years to win back if lost.


Numbers and facts are important because they define ultimate limits and capabilities, but numbers and facts don’t make decisions: People make decisions. Nowhere is this truer than in the United States satellite broadband market of late 2025. If we look strictly at the operational scoreboard, the game is over. Starlink has achieved a scale that no competitor can mathematically replicate within the relevant investment horizon. While the data based on now a bit over one million respondents from our Recon Analytics Telecom Pulse Service shows that Starlink holding a massive customer satisfaction lead in rural America over terrestrial as well as satellite legacy providers like HughesNet, dwelling on this gap is an exercise in archaeological irrelevance. HughesNet is effectively liquidating its business model, and ViaSat is pivoting away from it. Both are implicitly acknowledging that the laws of physics have rendered them obsolete. Rural telcos stuck with DSL are holding on for dear life in an era that is rapidly coming to an end. The war against legacy GEO is not just over; the battlefield has been cleared. When the last remnants of rural DSL are being swept away by its skyborne replacement is only a matter of a few years.

The real narrative is not about Starlink beating zombies; it is about the politically engineered survival of its future competitors. The industry is bifurcating into two distinct realities: SpaceX’s operational “rout” and the strategic mandates sustaining Amazon Leo and AST SpaceMobile. These companies matter not because they are currently beating Starlink on metrics—they aren’t—but because the U.S. government and the nation’s largest wireless carriers have decided that a Musk monopoly is strategically unacceptable. Consequently, we are witnessing the creation of a managed market where strategic intervention and corporate hedging sustain competitors that market forces alone would eliminate.

The Carrier Insurgency: The “Never Musk” Wager

While T-Mobile grabbed headlines by pairing with an iconic inventor and a proven technology years ahead of the competition, the most consequential satellite-communications decision of recent years happened quietly in AT&T’s and Verizon’s boardrooms in 2024. Their commitments of capital and spectrum to AST SpaceMobile weren’t bets on the best technology available: they were bets on strategic independence. Even in 2024, it was clear that AST was operationally behind, struggling with a single-digit satellite count while Starlink was deploying thousands. The carriers knew that AST’s service would likely launch later and offer less initial capacity than the vertically integrated juggernaut of SpaceX. They looked at the spreadsheets, saw the performance gap, and decided to stomach it.

This was a calculated strategic sacrifice. AT&T’s decision to lock into a binding agreement with AST through 2030 represents a deliberate strategy to preserve network sovereignty rather than a forced reaction to market constraints. Management feared, and correctly so, that utilizing Starlink would ultimately accelerate Elon Musk’s ambition to become a full-fledged service provider, leading to their own disintermediation as network operators. If they partnered with Starlink, they risked becoming mere resellers in a Musk-controlled ecosystem, effectively funding their own future competitor. Consequently, AT&T was willing to endure the short-term pain of AST’s operational delays to nurture a competitor that preserves their control, calculating that the cost of funding a future Starlink monopoly far exceeds the risks of supporting a slower, inferior alternative.

Verizon followed a similar, albeit more hedged, logic. Their $100 million investment in AST was a coldly calculated but necessary option premium. Verizon leadership recognized that T-Mobile’s exclusivity with SpaceX was temporary, but they also recognized that a world with only one satellite provider gives that provider infinite pricing power. By propping up AST, Verizon keeps a non-SpaceX option alive to discipline the market. They are funding AST not because the tech is currently better—the gap between AST’s 5 satellites and Starlink’s 660 D2C satellites is 100-to-1—but because the contract isn’t with Musk. AST has effectively become a compliance cost for the wireless industry, a tax paid by carriers to ensure they never have to bend the knee to SpaceX.

This “Not-Musk” imperative explains why the investment thesis for AST remains robust despite the fact that its primary differentiator—broadband to the phone—has been neutralized. SpaceX’s confirmed Q1 2026 rollout of full data and voice capabilities has effectively evaporated AST’s unique value proposition. Yet, the carriers cannot waver. The 2025 rupture between Donald Trump and Elon Musk only validated the carriers’ 2024 foresight: relying on a single, politically volatile billionaire for critical infrastructure is a fiduciary hazard. AT&T and Verizon are stuck with AST, and they are happy to be stuck, because the alternative is captivity.

Amazon Leo: The “Too Big to Fail” Regulatory Gamble

If the carriers are engineering AST’s survival through capital, the federal government is engineering Amazon Leo’s survival through regulation. Amazon Leo is not a standard growth story; it is a binary derivative trade on regulatory relief. The scale of Amazon’s deployment deficit is staggering. As of late 2025, Amazon has managed to place only 153 satellites into orbit, leaving a gap of 1,465 satellites against the FCC’s deadline requiring 1,618 by July 2026. This gap is mathematically uncloseable through launch cadence alone. Consequently, Amazon requires a waiver that would typically invite withering scrutiny.

However, Amazon has successfully constructed a regulatory shield by securing BEAD awards for 211,194 locations across 33 states. These awards create a government interest in Amazon’s success. State broadband offices, desperate to show competition, accepted Amazon’s paper promises over SpaceX’s operational reality, effectively making Amazon too big to fail without collapsing a critical federal program. If Amazon cannot illuminate these locations, states face clawbacks and the administration faces a failure of its signature infrastructure project.

The most dominant policy force in the market today is the BEAD program. Amazon Leo’s dominance of the BEAD program was achieved by aggressively buying the market with average bids of just $560 per location, effectively undercutting Starlink by a factor of three. This secures a guaranteed revenue floor estimated at $177 million annually, which exists independent of consumer preference. Regulators are expected to grant the accommodation to avoid entrenching a SpaceX monopoly, using the waiver to provide political cover while maintaining the appearance of regulatory neutrality. The Trump administration increasingly favors Jeff Bezos over the volatile Elon Musk in this context, rendering regulatory accommodation probable. Amazon Leo survives not because it executed, but because the government cannot afford to let it die.

The Political Overlay: 2025 as an Accelerant

While the carriers made their anti-monopoly decisions in 2024, the political volatility of 2025 acted as a powerful accelerant, hardening the “Not-Musk” resolve across the ecosystem. The alliance between Donald Trump and Elon Musk collapsed in June 2025 due to disputes over fiscal policy and devolved into name calling. Although a pragmatic reconciliation began in November, the era of automatic regulatory preference for SpaceX is finished. The relationship has stabilized at “neutral,” a significant downgrade from the “favored” status Musk enjoyed early in the year.

This political oscillation drives strategic positioning. The Pentagon, seeking to hedge political risk rather than simply improve capability, directed “Golden Dome” defense planners to diversify away from exclusive reliance on SpaceX in favor of Amazon. This directive to “diversify” is now embedded in procurement logic, creating a permanent, protected market for a “second source” regardless of the headlines. Just as AT&T and Verizon funded AST to avoid commercial captivity, the Department of Defense is funding Amazon and AST to avoid strategic captivity.

The Reality of Market Bifurcation

The satellite internet industry has organized into four distinct competitive segments, and understanding this structure is essential because winners in one segment do not necessarily dominate the others. While Starlink dominates the LEO consumer broadband market with a +42 Net Promoter Score, the government and carriers have effectively decided to subsidize competitors to ensure market health. This creates a floor for Amazon and AST, and a ceiling on Starlink’s monopoly power.

The numbers are definitive: Starlink’s operational dominance provides a shield that regulation cannot easily penetrate. Its satisfaction lead creates a political asset, insulating the company because no administration can politically afford to disconnect rural American voters. However, the strategic landscape proves that performance is not the only metric that matters. Amazon Leo’s 211,194 committed BEAD locations provide a survival path even if the FCC denies a consumer waiver, converting it into a government-subsidized utility. AST SpaceMobile’s binding contracts with AT&T and Verizon ensure it remains a viable entity, serving as the industry’s indispensable “Plan B”.

Ultimately, the satellite industry acts as a mirror for the broader political economy. The “SpaceX Paradox” defines Amazon’s desperate position: to compete with Starlink, Amazon was forced to contract launches from its primary competitor, implicitly admitting that SpaceX’s capacity was necessary for its own survival. Yet, Jeff Bezos has successfully positioned himself as a “responsible” alternative, securing a vital revenue lifeline to sustain Amazon Leo. The market has bifurcated: Starlink wins on physics and performance in the consumer zone, while Amazon and AST win on politics and diversity mandates in the regulatory and carrier zones.

For investors and executives, the lesson is clear: The narrative of “failure” surrounding legacy providers is simply the sound of the past dying; ignore it. The real signal is the deliberate, expensive, and strategic effort by the world’s largest telecom companies to prevent a SpaceX monopoly. AT&T and Verizon knew exactly what they were buying in 2024: an inferior product that offered the superior benefit of independence. They decided to stomach the lag, the risk, and the cost because the alternative was a future where Elon Musk held the keys to their network. The data tells us who has the best product, but the strategy tells us who will be allowed to survive.

If you want to read more about the interplay between the satellite and broadband industry have a look here.
https://www.reconanalytics.com/products/2027-november-satellite-report-vf/

Commerce Secretary Lutnik signaled in an interview with Broadband Breakfast on March 5th, 2025 that the US government will rethink the BEAD program so that Americans “get the benefit of the bargain.” He elaborated that it could mean that homes get broadband through satellite instead of fiber. “We want the lowest cost broadband access to Americans,” he said.

Secretary Lutnik gets it. Connecting a location to broadband for $10k-$30k makes more sense than spending $60k to do the same thing. By approaching the issue from a technology-neutral perspective, we can connect a lot more people for a lot less money while improving connectivity and satisfaction with the connection.

From February 28th, 2024, to February 28th, 2025, Recon Analytics surveyed 160,848 people in the United States and asked them about their broadband experience with their current provider.

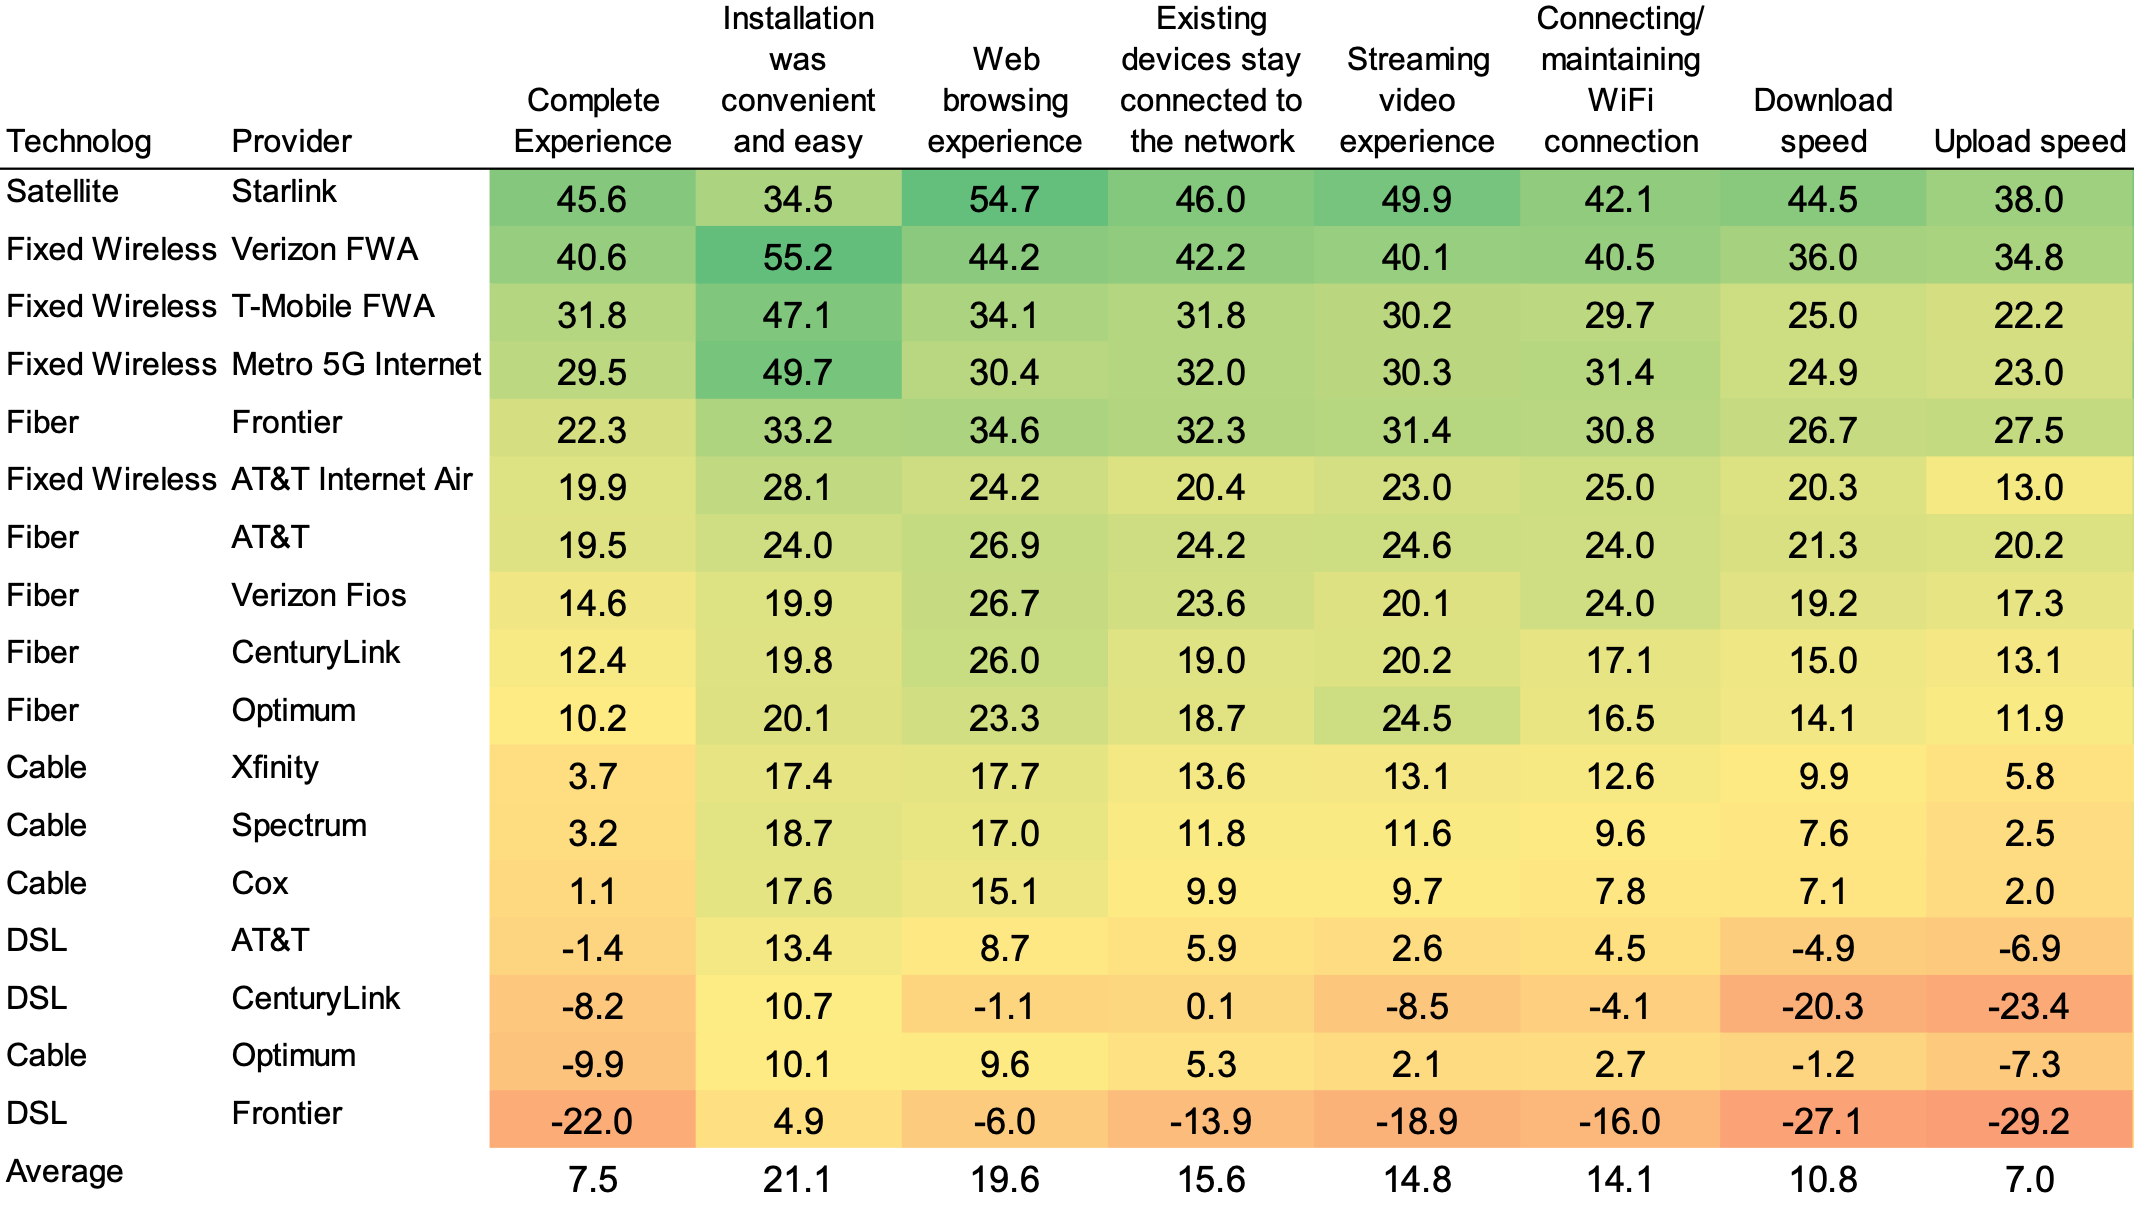
To determine satisfaction with their service, we asked consumers a standard net promoter question as developed by Bain, but modified to ask about specific components of the customer experience. Below you see a heatmap of Recon Analytics’ component NPS scores for connectivity. I omitted the customer interaction part of the heatmap for readability.

The 1,113 Starlink subscribers we interviewed over the last year were the most satisfied, followed by consumers of fixed wireless (FWA) with cable, and DSL customers being the least happy. Why are Starlink customers and FWA customers happier than cable and DLS?

While Starlink and FWA can be slower than speeds over cable, most consumers are not engineers or economists who make decisions based solely on technical merit or price. In the case of both Starlink and FWA, our data confirms that customers value the fact that the technology solution is easy to install and easy to get rid of if the consumer is not happy. In Starlink’s case, we have about three times as many former Starlink customers as current Starlink customers. This indicates that there are quite a few people who were unhappy with the solution and swapped out for a different one.

At the same time, the people for whom Starlink or FWA works are very happy with it, especially in comparison to what they had before. Interestingly, we consistently find in our polling data that the higher the cost for a service, the lower consumer satisfaction is, all other things held equal. The low satisfaction scores for cable, even though cable internet service is substantially cheaper than fiber, is a clear indication that cable needs to do a much better job in serving its customers. As confirmed in the quarterly reported financial data, customers leave services with low satisfaction and join services with high satisfaction. In the home internet case, customers choose a more expensive service because, in their experience, the cheaper service is not worth it.

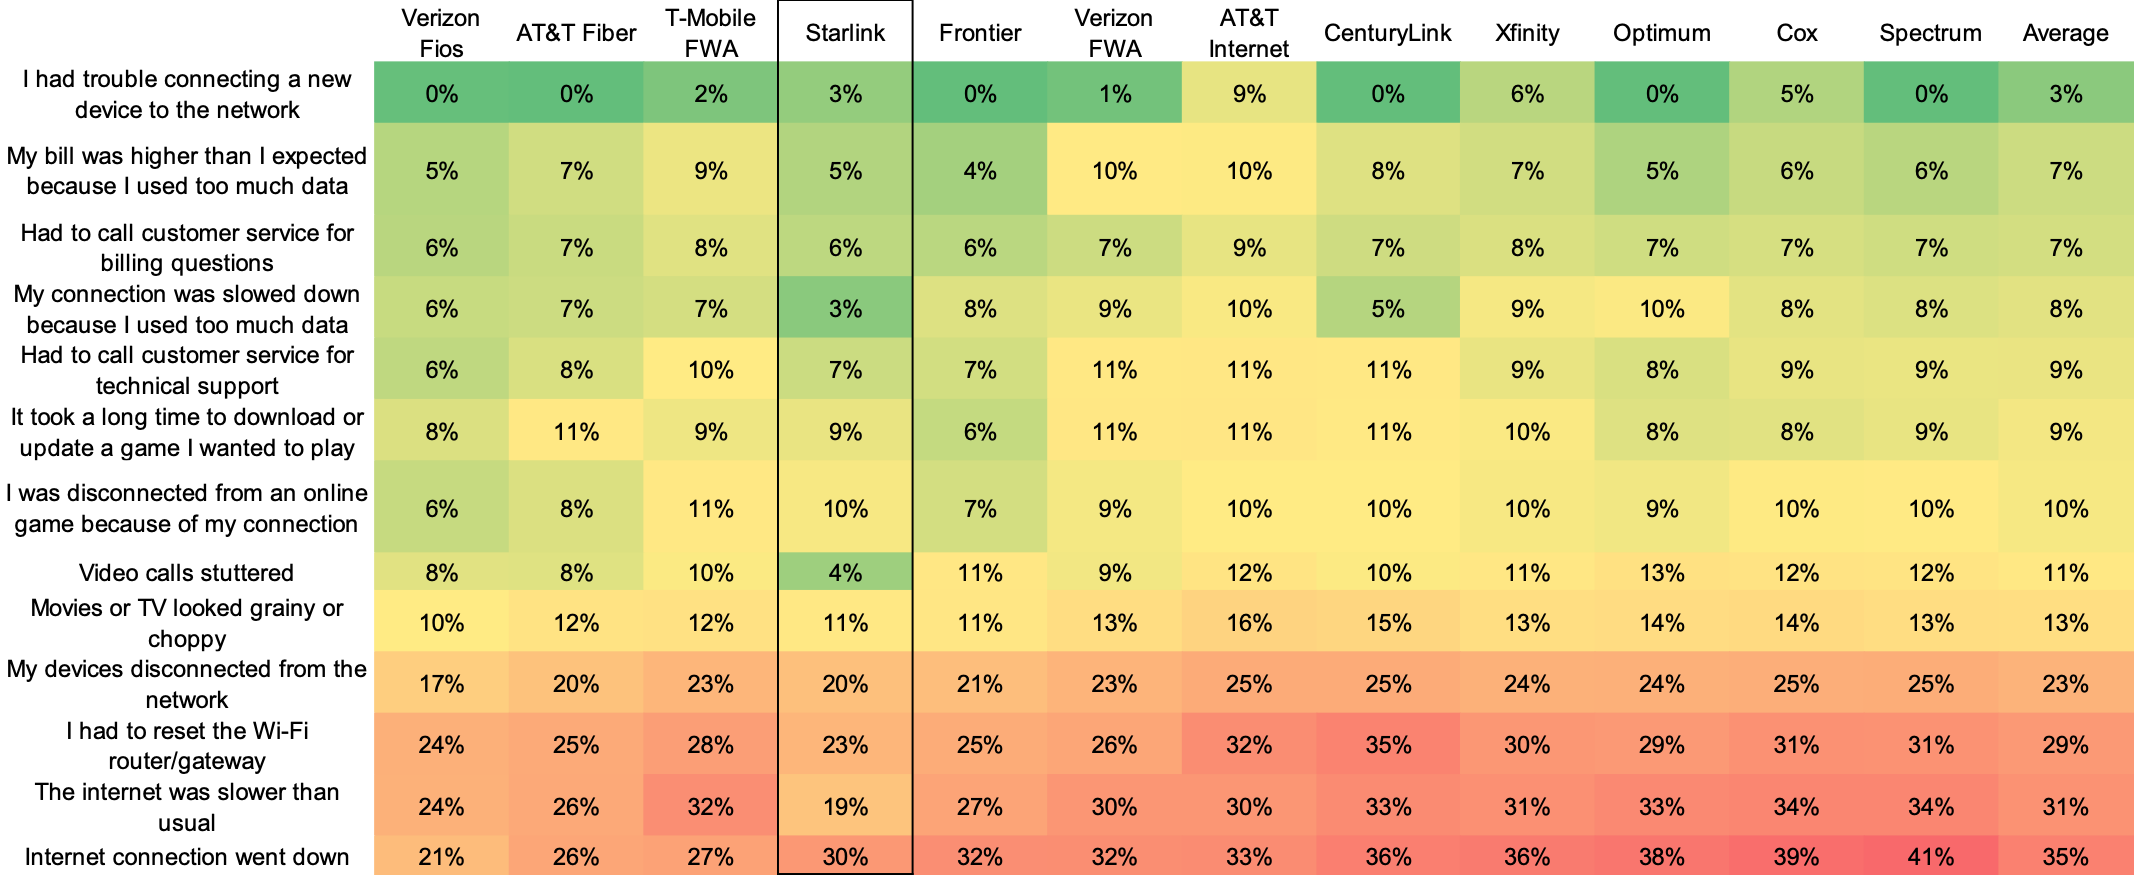
We are also seeing in the data that the Starlink and FWA routers are state-of-the-art equipment. Investment in good routers leads to better scores for how well existing devices stay connected to the Wi-Fi network and how easy it is to connect to Wi-Fi. It also aids in every other connectivity and customer issues metric. This is demonstrated again in the table below.

We are also asking all of our home internet respondents how often they have subjectively experienced internet issues in the last 90 days. The data below is again from the 160,848 people we surveyed over the last year.

What is striking is how well Fiber, FWA, and Starlink are performing when it comes to reliability. When looking at reliability from a customer perspective, it is the interplay between the connection, which is determined by network technology; the router used or supplied; and the end user equipment. The end user equipment is the same for every customer – a mix of smartphones, laptops, desktops, and other connected devices. While Verizon FiOS and AT&T Fiber customers report fewer instances of their internet connection going down, the FWA and Starlink routers are able to mitigate a lot of the more difficult connection technology challenges.

When comparing the data presented in this research note with what was presented six months ago, the Starlink scores for connectivity increased as the company launched more satellites during that period. As Starlink continues to launch more satellites, its scores will change depending on what increases faster – the number of satellites or the number of customers.

Furthermore, it is interesting to see where Starlink customers came from. Eighty-five percent of Starlink respondents are from rural areas, consistent with Starlink’s reporting of where it sells. Almost 31% came from small ISPs. For more than 11% of respondents, Starlink is the first home internet provider that they have, followed by CenturyLink, Charter, Frontier and Comcast, who provide a lot of internet coverage in rural areas.

Recon Analytics data shows that a technology-neutral approach is the right way to go for allocating federal dollars to get affordable broadband out to as many Americans as will take it. There are many Americans, especially in very rural areas, who are very happy with Starlink’s service. Fixed wireless is also solving the broadband rubric for many customers in a satisfactory way. Fixed wireless is especially valuable in less densely populated areas, where ample spectrum and thereby speed and capacity is shared among fewer people resulting in higher speeds. Fiber, without a doubt, is the workhorse technology for more densely populated areas, where satellite and FWA do not have sufficient capacity given the current licensed full-power spectrum constraints to serve customers well.

What we need, and what Secretary Lutnik rightfully alluded to, is a technology-neutral approach where the Americans can choose how they want to be connected at the lowest price considering the circumstances.

Americans love the internet, accessing it from home and on the road. Until 2007, Americans essentially had two choices when it came to home internet: cable internet or DSL. To the cable industries great credit, they were the first to provide high speed internet access to most Americans with DSL, a slow “other choice” if cable was not available or was too expensive. But beginning in 2007, the telecom companies began to build out fiber, first with Verizon FiOS, and then by AT&T launching fiber service in 2013. By launching fiber networks, telecom companies brought competition to cable in the home broadband market and offered Americans more choices for connecting to the Internet.

In the last three years, the competitive landscape has changed again, for the benefit of American consumers of all stripes.  The mobile network operators have launched Fixed Wireless Access (FWA) and, as we saw during Hurricane Helene, satellite provider Starlink proved its prowess in rural, hard to reach geographies.

FWA has become such a popular choice that the cable companies are losing home internet customers to FWA providers, a trend that has thumped the cablecos market cap. Since launch, Verizon, T-Mobile and AT&T added 10.675 million customers to their FWA service.  And almost all of those subscribers came from cable companies.

FWA service is typically slightly less expensive that fiber or cable home internet, but its satisfaction scores across all 16 cNPS categories is higher.

Part of the reason for the superior cNPS scores are a better purchasing and installation experience for consumers, lower price points and the ability to easily return the product if it does not meet the customer’s satisfaction. This leads to the customers who use the service to be happy with it, while the unhappy customers cancel the service, return the router and continue service with their existing provider and continue to be less than happy with them.

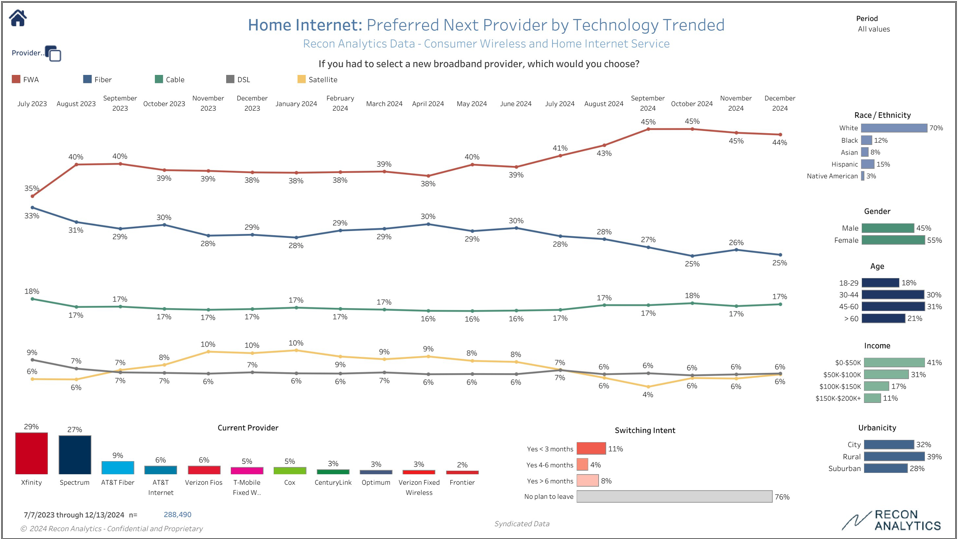
The high satisfaction and lower price for FWA and the dissatisfaction with the other choices available has led FWA to become the preferred next home internet provider of choice for Americans.

Based on interviews with 288,490 Americans conducted between July 2023 and December 2024, 44% of Americans would choose an FWA as their next provider if they would have to make a choice other than their existing provider, 25% would choose a fiber provider, 17% a cable provider, and 6% each would choose DSL or a satellite provider (predominantly Starlink.)

The change in customer preferences is also an opportunity. FWA is the first home internet offer that is being advertised on a nationwide basis, both on a standalone and converged basis. More than 70% of FWA customers are using the mobile solution of the same provider. We are also increasingly seeing a remarkable amount of customers who are switching from one FWA provider to another indicating both a preference for FWA as well as a high aversion to the available wired solutions available. It is also a wakeup call for existing providers, especially cable, to improve their service, both on a technical basis with DOCSIS 4.0 and a relational basis in how they interact with their customers. We are full of hope as some cable providers are introducing NPS as a metric they look at and full of dismay as FWA is being described as CPI or Cell Phone Internet. By describing FWA as cell phone internet, these cable providers do themselves a disservice as cell phones have nothing to do with FWA other than the network they use and shows a blindness to the real threat FWA provides to them. As long as cable views FWA as CPI it will continue to lose as it lives in its own world disconnected from the preferences of everyday Americans.

This has interesting implications for the spectrum policy world. Cable, understandably, is trying to prevent new licensed, full power spectrum to be authorized for cellular use. Why would they? That additional spectrum will enable the mobile operators to offer even more FWA options.   While the wireless industry is pushing hard for more full power, commercial spectrum, it is not a done deal.   In 2024, we have seen FWA speeds and the availability to sign up with FWA in urban market decline indicating that the growth of FWA is becoming more of a supply issue than a lack of demand. Hence the need for more full power spectrum to amp up network capacity to support more FWA.

The outgoing 118th Congress failed to provide Americans with a spectrum pipeline and the FCC with general spectrum authority (Congress provided for temporary spectrum authority to reauction the returned AWS-3 licenses.) The chances that the incoming 119th Congress that takes over in 2025 will provide a spectrum pipeline with licensed, full-powered spectrum is much higher. The last Trump White House leaned much more heavily on the Department of Defense and was able to clear the 3.45 GHz spectrum for commercial use in a record one-year time period. The incoming Senate Commerce Committee Chairman, Senator Cruz (R-TX), has also traditionally been less accommodating to Department of Defense preferences and FCC failure to live up to its congressionally mandated requirements.

In a nutshell, FWA has higher satisfaction scores than any other technology and more Americans want FWA as the way they connect to the internet than any other choice. It is up to Congress to decide if Americans get their wish.

Sometimes old album titles say it best. Today, AT&T marks the start of the expansion of AT&T’s fixed wireless home internet service called AT&T Internet Air. After offering it in its DSL footprint for the last few months, it is now becoming the third nationwide mobile network operator (MNO) to launch a 5G (where available) internet offer.

AT&T is starting in Los Angeles, Philadelphia, Cincinnati, Harrisburg/Lancaster/Lebanon, PA; Pittsburgh, Chicago, Detroit, Flint-Saginaw-Bay City, MI; Las Vegas, Minneapolis-St. Paul, Phoenix (Prescott), AZ; Portland, OR; Salt Lake City, Seattle-Tacoma, Tampa-St. Petersburg (Sarasota), and Hartford-New-Haven, CT. Notably, Los Angeles is Charter’s largest market and a T-Mobile FWA stronghold, Philadelphia is Comcast’s home market, and Seattle is T-Mobile’s home market. If the carriers are looking for attention, these launch markets are certainly going to attract it. Another very interesting market is Phoenix. Gigapower, a joint venture in which AT&T is involved, is building out fiber in Mesa, AZ. While the two are about 100 miles apart, it will be interesting to see how the two technologies will be adopted in the same market.

With nationwide combined 3.45 GHz and C-Band of 120 MHz on average, and with at least 100 MHz in every market, AT&T can put significant bandwidth behind its FWA offer. The theoretical maximum speed achievable with 100 MHz of spectrum is 2.3 Gbit/s. It is important to keep in mind that what is possible in theory is also possible in reality – and that wireless is a shared resource. Will someone sitting next to a tower be the only person on the cell to get 2.3 Gbit/s? Possibly, but even though quite a few wireless speed testers have reported wireless download speeds of 600 to 800 Mbit/s, it is far from certain on a loaded network. Even half the theoretical speed is still more than respectable. Quieter than its competitors, AT&T has rolled out its mid-band network to more than 175 million pops.

AT&T Mid-Band Spectrum Depth of 3.45 GHz and C-Band