

Consumer AI is young enough that market positions are still fluid. The leading providers are spending heavily on models and computing capacity, and the subscription revenue that helps pay for it comes from the roughly one in four AI users who pay for a tool. Every few months a provider releases a model that does some tasks better than its rivals, and anyone can try it within minutes. There is no contract to end and no number to port. Whether people actually move when a better tool appears, measured here as AI tool switching, shows which providers are building the habits and the spending that will be hard to dislodge once the market settles.
The question also tests a strategic bet. Companies that already own a screen or a speaker in the home have built an assistant into it, betting that distribution will decide this market. Standalone AI tools are betting that people will go looking for a better product. Where switchers land, and the reasons they give, is the most direct evidence of which bet is paying off.
Measuring it takes care, because AI tool switching works differently from switching in the subscription businesses it is usually compared with. A wireless customer who ports a number leaves one carrier for another, and a household that cancels a streaming service loses its shows. Most AI users never face that choice, because they already use more than one tool. Among the AI users Recon Analytics surveyed in the 13 weeks to September 18, 2026, 62% had tried two or more AI tools, 52% named a second tool they use regularly and 29% named a third. Someone can draft in Claude, look things up in Gemini and keep ChatGPT open for everything else. Adding a tool costs little and dropping one is rarely necessary, so a count of a product’s users says little about whether it is gaining ground.
Two positions in that rotation still carry weight. One is the primary tool, the one a person reaches for first and uses most. The other is the subscription, and the two travel together. Of AI users who pay for any AI tool, 87% pay for their primary; only 13% pay solely for a second or third tool. Paying rates also fall down the list: 22% of AI users pay for their primary tool, against 9% of second-tool users who pay for that tool. When a person changes primary tool, the default habit and usually the spending move with it. That change is the AI equivalent of a carrier switch for the purposes of this note, and it is what we measure here. AI Pulse is a consumer and prosumer survey: it captures the tools individuals choose for personal use and for their own work, and it does not measure enterprise contracts or developers buying AI models through an API.
AI tool switching runs at about 6% of AI users a month
Of 31,569 AI users asked, 18% said they had changed their primary AI tool in the previous three months, an average of 6% a month. The monthly rate has stayed between 5% and 7% in every weekly wave since the question was added in December 2025. That is roughly six to seven times the monthly postpaid churn the three national wireless carriers reported for the second quarter of 2026 (i). The comparison overstates the disruption in one respect: a carrier disconnect ends a paid relationship, while most people who switch AI tools keep using the old one. About two-thirds of switchers answered a follow-up on the other tools they use, and about 90% of them still use the tool they left as their second or third.
Heavy users drive the rate. People who use AI several times a day switch at 9% a month; those who use it a few times a month switch at 3%. Frequent users were more likely to switch, and they also made up a larger share of the people who answered the switching question than they do of AI users overall. Adjusted to the usage mix of all AI users, the rate is still about 6% of AI users in an average month. IT decision makers, the respondents responsible for AI choices for their firm or department and more often developers and product leaders, make up about a fifth of those asked. They switch at 31% over three months, roughly twice the rate of everyone else. Without them the monthly rate is 5%. Over a year, switches add up to nearly three-quarters of the AI user base, though some of those are the same people switching more than once.
Three tools gain from AI tool switching
Among the 5,751 switchers who named both the tool they left and the tool they chose, 40% moved to ChatGPT and 33% left it, a net gain equal to about 8% of switchers. Claude took 11% and lost 7%, a net gain of about 4%. Google Gemini took 24% and lost 22%, a net gain of about 3%. Every other tool in the survey lost ground or broke even.
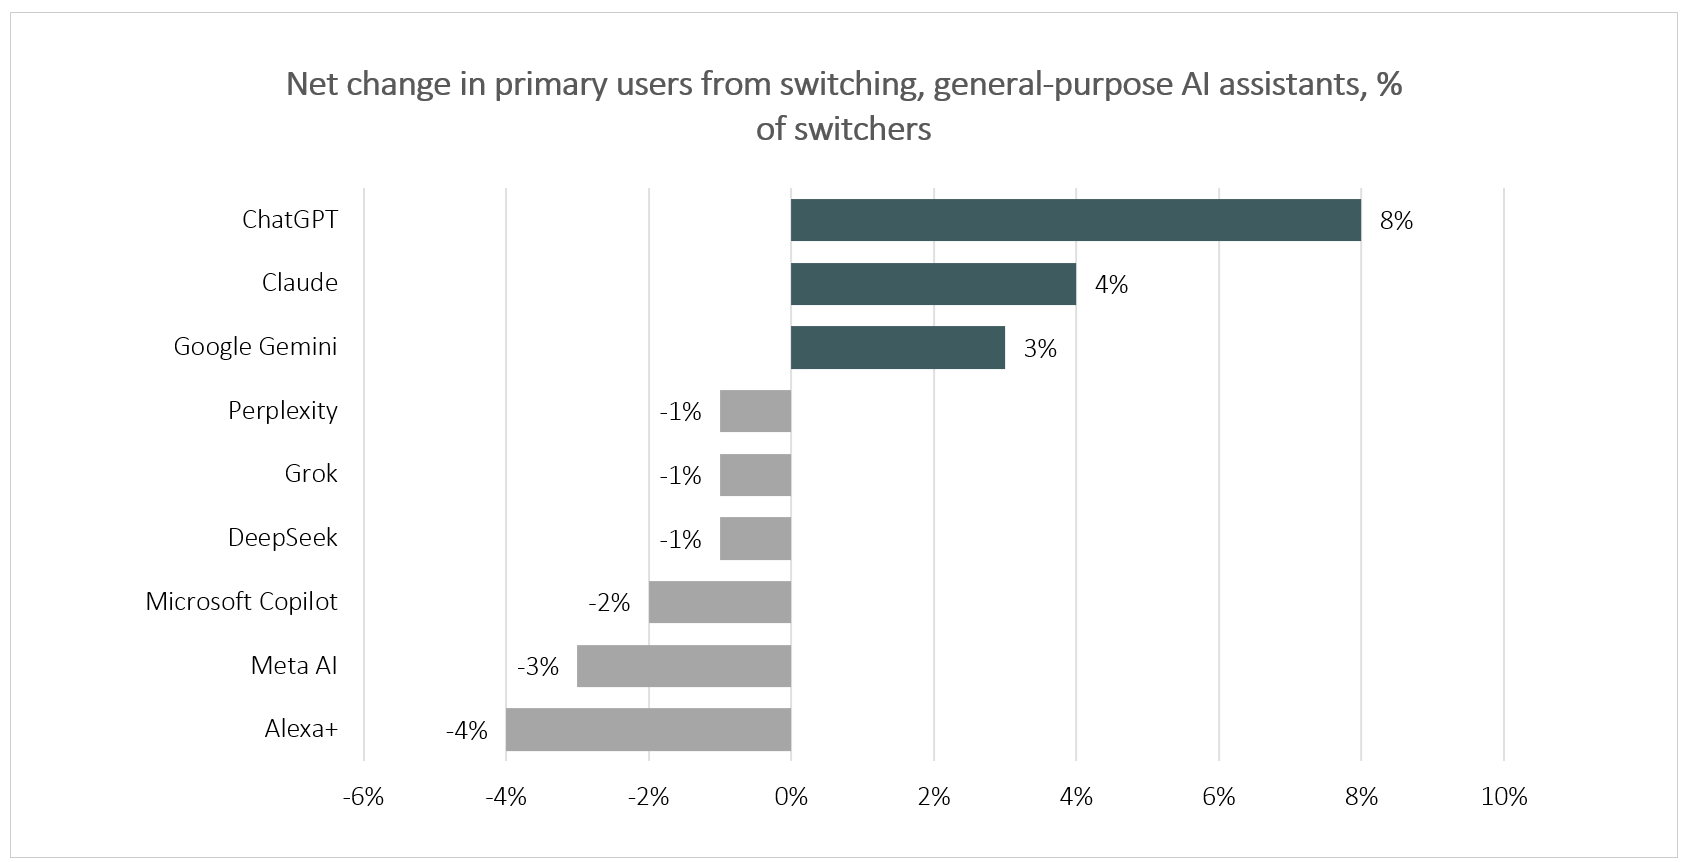
Chart 1: Net change in primary users from AI tool switching by general-purpose assistant, percent of switchers: ChatGPT +8, Claude +4, Google Gemini +3, Alexa+ -4, Meta AI -3, Microsoft Copilot -2, DeepSeek, Grok and Perplexity -1 each, AI Pulse, June to September 2026
Source: Recon Analytics AI Pulse, 5,751 switchers naming both tools, 13 weekly waves opening June 26 to September 18, 2026. General-purpose assistants with the largest net changes shown; phone-based assistants (Apple Intelligence, Galaxy AI) are discussed separately.
Between the two largest tools the exchange is close: of people who switched between ChatGPT and Gemini, 52% chose ChatGPT. Between ChatGPT and Claude, 63% chose Claude. ChatGPT’s lead among switchers leans on IT decision makers, who account for about three-quarters of its net gain. Among all other respondents, Gemini gains about 1.3 primary users for each one it loses, against about 1.1 for ChatGPT. Winning switchers has also not stopped the share of panel respondents naming ChatGPT as their primary tool from slipping, from 47% to 45% between the last two quarters.
Pre-installed assistants lose the most
Among general-purpose assistants, the largest net losses as a share of switchers belong to Alexa+ at 4%, Meta AI at 3% and Microsoft Copilot at 2%, followed by DeepSeek, Grok and Perplexity at about 1% each. The three largest losers come built into something the person already owns: a speaker, a social feed and Microsoft 365. Apple Intelligence and Samsung’s Galaxy AI each lost about 1% as well. They are phone features with a narrower set of capabilities and no paid tier of their own, so we keep them out of the comparison with the general-purpose assistants.
Being built in keeps these assistants in the rotation, since a demoted tool usually stays in use, yet in this data it has rarely won them the primary slot. Gemini is the exception among embedded assistants, collecting more primary users than it gives up. Fewer than one in ten of its arrivals wrote in a reason, and about a quarter of those point to its placement, mentioning Google search, Chrome, Android or their phone; a few describe AI answers inside Google search, which blurs the line between changing tools and searching. “It is part of Google and just starts when I type on Google search,” one wrote. Its arrivals still rank answer quality first about as often as ChatGPT’s do.
Claude wins switchers at the best ratio, from a small base
About 4% of AI users in our panel name Claude as their primary tool, well behind ChatGPT and Gemini, yet it has the best exchange rate among switchers. For every primary user it gave up this quarter it gained 1.7, against 1.2 for ChatGPT and 1.1 for Gemini. In the previous 13 weeks the ratios were 1.5, 1.4 and 1.1, with Claude and ChatGPT close to level.
The small base needs context. Anthropic earns most of its revenue from businesses and developers, with usage-priced API calls estimated at about 80% of its total (ii) and a consumer and prosumer panel sees little of that. Claude’s position here measures its pull with individual users and says less about the company’s overall fortunes.
Claude also turns over fastest. Its arrivals this quarter equal 52% of its primary users at the start of the quarter, and its departures 31%. For ChatGPT the figures are 19% and 15%, and for Gemini 18% and 16%. A quarter earlier Claude’s arrivals equaled 63% of its primary users at the start of that quarter, and its departures 41%. The better ratio came from fewer users leaving, while arrivals eased.
| ChatGPT | Claude | Gemini | |
| Gained per user lost, Jun-Sep | 1.2 | 1.7 | 1.1 |
| Gained per user lost, Mar-Jun | 1.4 | 1.5 | 1.1 |
| Arrivals, % of starting users | 19% | 52% | 18% |
| Departures, % of starting users | 15% | 31% | 16% |
Table: Primary users gained per user lost and quarterly turnover for ChatGPT (1.2), Claude (1.7) and Google Gemini (1.1), June to September 2026 vs. March to June 2026, AI Pulse
Source: Recon Analytics AI Pulse, 13 weekly waves opening June 26 to September 18, 2026; prior quarter opening March 27 to June 19, 2026.
Switchers pay more, mostly because of who they are
Switchers pay at a higher rate than users who stay with their tool, though much of the difference comes from who switches. Switchers include more heavy users and more IT decision makers, and they head for tools that sell subscriptions. Compared with stayers who match them on tool, usage frequency and IT decision-making role, the gap narrows to about 4 points. Within ChatGPT and Gemini, the share of new arrivals who pay is more than 10 points higher than among existing users. At Claude, whose base already pays at a high rate, the two are close.
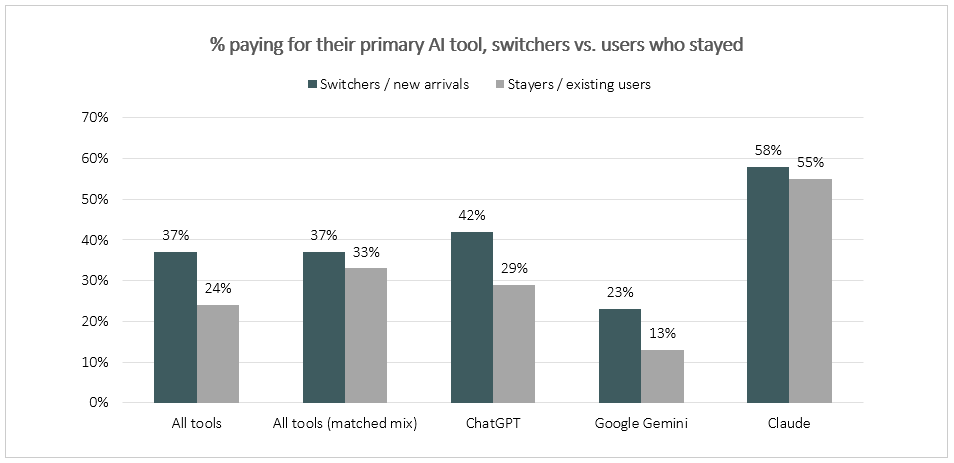
Chart 2: Percent paying for their primary AI tool, switchers vs. stayers: all tools 37% vs. 24%, matched mix 37% vs. 33%, ChatGPT 42% vs. 29%, Gemini 23% vs. 13%, Claude 58% vs. 55%, AI Pulse, June to September 2026
Source: Recon Analytics AI Pulse, 13 weekly waves opening June 26 to September 18, 2026. Percent using a paid version of their primary AI tool. Matched mix adjusts stayers to the switchers’ mix of tool, usage frequency and IT decision-making role.
Some of that money is personal spending on work tools. Of paying switchers, 28% pay out of pocket for a tool they use for work, the same share as paying stayers. Because more switchers pay, that group makes up 10% of all switchers against 6% of stayers. Copilot runs the other way: 65% of its paying arrivals have an employer or team covering the cost.
Winning a payer does not guarantee keeping one. In AI Pulse waves through early September 2026, 12% of current paying users said they had canceled an AI subscription in the previous three months. Among everyone who has ever paid for one, the figure was 17%. A provider that wins a switcher still has to keep that person paying, and with about one in six past subscribers canceling in a single quarter, keeping them after the switch deserves as much attention as winning them.
Answer quality leads AI tool switching, with curiosity close behind
Asked to rank their reasons for switching, switchers most often put better answers first, with wanting to try something new close behind. Lower cost and a less restrictive free tier together trail answer quality alone. Claude’s arrivals are the most deliberate of the three gaining tools: 29% ranked answer quality first and 7% curiosity, and they cited better features and recommendations more often than ChatGPT or Gemini arrivals. For ChatGPT and Gemini arrivals the two leading reasons ran level, at 17% to 19% each.
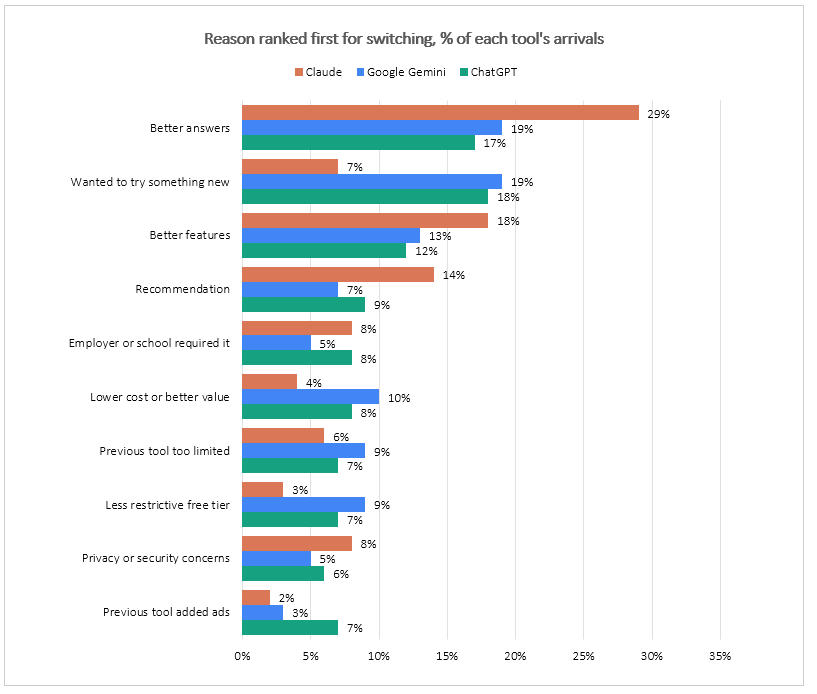
Source: Recon Analytics AI Pulse, 13 weekly waves opening June 26 to September 18, 2026. Share of each tool’s arrivals who ranked each reason first: 2,291 to ChatGPT, 1,331 to Google Gemini and 614 to Claude.
What this means for AI providers
Because people keep several AI tools at once, total users and downloads are weak guides to competitive position. The tool a person reaches for first, and pays for, is the better measure, and it changes hands often enough to track quarter by quarter. For standalone providers, the work is winning heavy users and IT decision makers on answer quality, then keeping them paying after the switch. For companies with an assistant built into a phone, speaker or social app, placement keeps the assistant in use, yet it has rarely made it the one people choose first. Gemini, whose arrivals cite both its placement and its answers, is the case to watch.
Some readings in the coming quarters would change this picture. If built-in assistants start collecting more primary users than they lose for two quarters running, placement is beginning to win the primary slot. A rise in switchers who say an employer or school required the change, 9% as of September 2026, would mean companies are taking the choice away from individuals, which favors tools sold through IT departments. If the weekly switching rate falls below 5% for a month or more, users are settling on a primary tool and the window to win them is closing. AI Pulse tracks each of these weekly.
Source: Recon Analytics AI Pulse, US adults, 13 weekly waves opening June 26 to September 18, 2026, data pulled October 7, 2026: 85,083 respondents, 46,851 AI users, 31,569 asked the switching question. Multi-tool use and payment by tool position are among the 46,275 AI users who named a primary tool. AI users are respondents who use AI at least a few times a month. IT decision makers are respondents responsible for firm- or department-level AI decisions. Shares of primary tool describe panel respondents and are not projected to the US population of AI users. The switching question asks whether a person changed primary tool in the past three months, so the three-month and monthly rates count people: someone who switched twice in that period counts once, and the monthly rate is the three-month rate divided by three, assuming switches are spread evenly. The annual figure is four times the three-month rate, so a person who switches in more than one quarter counts more than once. The adjusted rate applies each usage-frequency group’s switching rate to the frequency mix of all AI users. Net flows use the 5,751 switchers who named both tools: ChatGPT gained 2,325 and gave up 1,871; Claude 633 and 376; Google Gemini 1,400 and 1,251; Alexa+ 253 and 463; Meta AI 150 and 316; Microsoft Copilot 388 and 496. A tool’s starting users for a quarter are its users who did not switch plus its departures. The matched paid comparison adjusts stayers’ paid rates by tool, usage frequency and IT decision-making role to the switchers’ mix. Who pays uses the 2,118 paying switchers and 5,670 paying stayers who said why they pay; employer-funded means employer or team payment was among their reasons. Reasons are shares of switchers who ranked a first reason (5,607 overall). Gemini arrivals’ written reasons: 119, about 9% of its arrivals, self-selected. Cancellations: three waves to September 4, 2026, 1,449 current paying users and 3,131 respondents who have ever paid. The 13-week window matches the question’s three-month recall, so the two quarters’ recalled switches overlap by about half. The panel is demographically representative of US adults through quotas set during fielding, so no post-fielding weights are applied. Percentages use the answered base and are rounded to whole points, each on its own, so a rounded net figure can differ by a point from the difference of its rounded parts. The survey lists Galaxy AI as Samsung AI and Meta AI as Meta/Facebook/Instagram.
Contact: Tanya Masiello, Analyst and Managing Director, Recon Analytics, [email protected]
